Building a Bright and Sustainable Future Together
As a small business owner, you recognize the significance of looking after your team and fostering a nurturing work environment. One method to demonstrate this is by providing a robust group benefits plan. This not only reflects your dedication to your team’s well-being but also is instrumental in drawing and retaining the best talent. Dive into the realm of group benefits and discover how to select and tailor the ideal plan for your small enterprise.
Understanding the Basics of Group Benefits
Group benefits plans are crafted to offer a variety of health, financial, and wellness advantages to your team members. These packages can encompass health and dental insurance, life and disability insurance, retirement savings alternatives, and more. The main benefit of a group benefits plan is its ability to distribute the risk among your team, making coverage more cost-effective and reachable for all.
Step 1: Assess Your Business Needs
Before diving into a group benefits plan, it’s vital to evaluate the requirements of your business and your team. Ponder over these questions:
Step 2: Collaborate with a Benefits Specialist
Teaming up with a benefits specialist is akin to having a navigator on your quest to devise the perfect plan. They will assist you in traversing the intricate landscape of insurance choices, rules, and compliance mandates. They’ll engage closely with you to grasp the distinct needs of your business and craft a plan that matches your budget and principles.
Step 3: Customize Your Plan
Adaptability is paramount when shaping a benefits plan that appeals to your team. Here are some avenues for personalization:
Step 4: Educate Your Employees
The efficacy of a group benefits plan hinges on transparent communication and enlightenment. Ensure your team comprehends the worth of the benefits provided and the methods to utilize them optimally. Arrange seminars, online sessions, or informational meetups to aid them in making knowledgeable choices about their coverage.
Step 5: Regularly Review and Adjust
The dynamics of your business and the needs of your team will transform over time. Hence, it’s crucial to revisit your group benefits plan annually and make requisite modifications. This guarantees that your plan stays in sync with your objectives and consistently delivers value to your team.
Building a Sustainable Future Together
As you embark on the path of picking and personalizing a group benefits plan for your small enterprise, bear in mind that your collaboration with your team is central to the process. By placing their welfare at the forefront and presenting a comprehensive benefits package, you’re not merely paving a brighter path for your team but also cultivating a sustainable work setting that promotes allegiance, efficiency, and expansion.
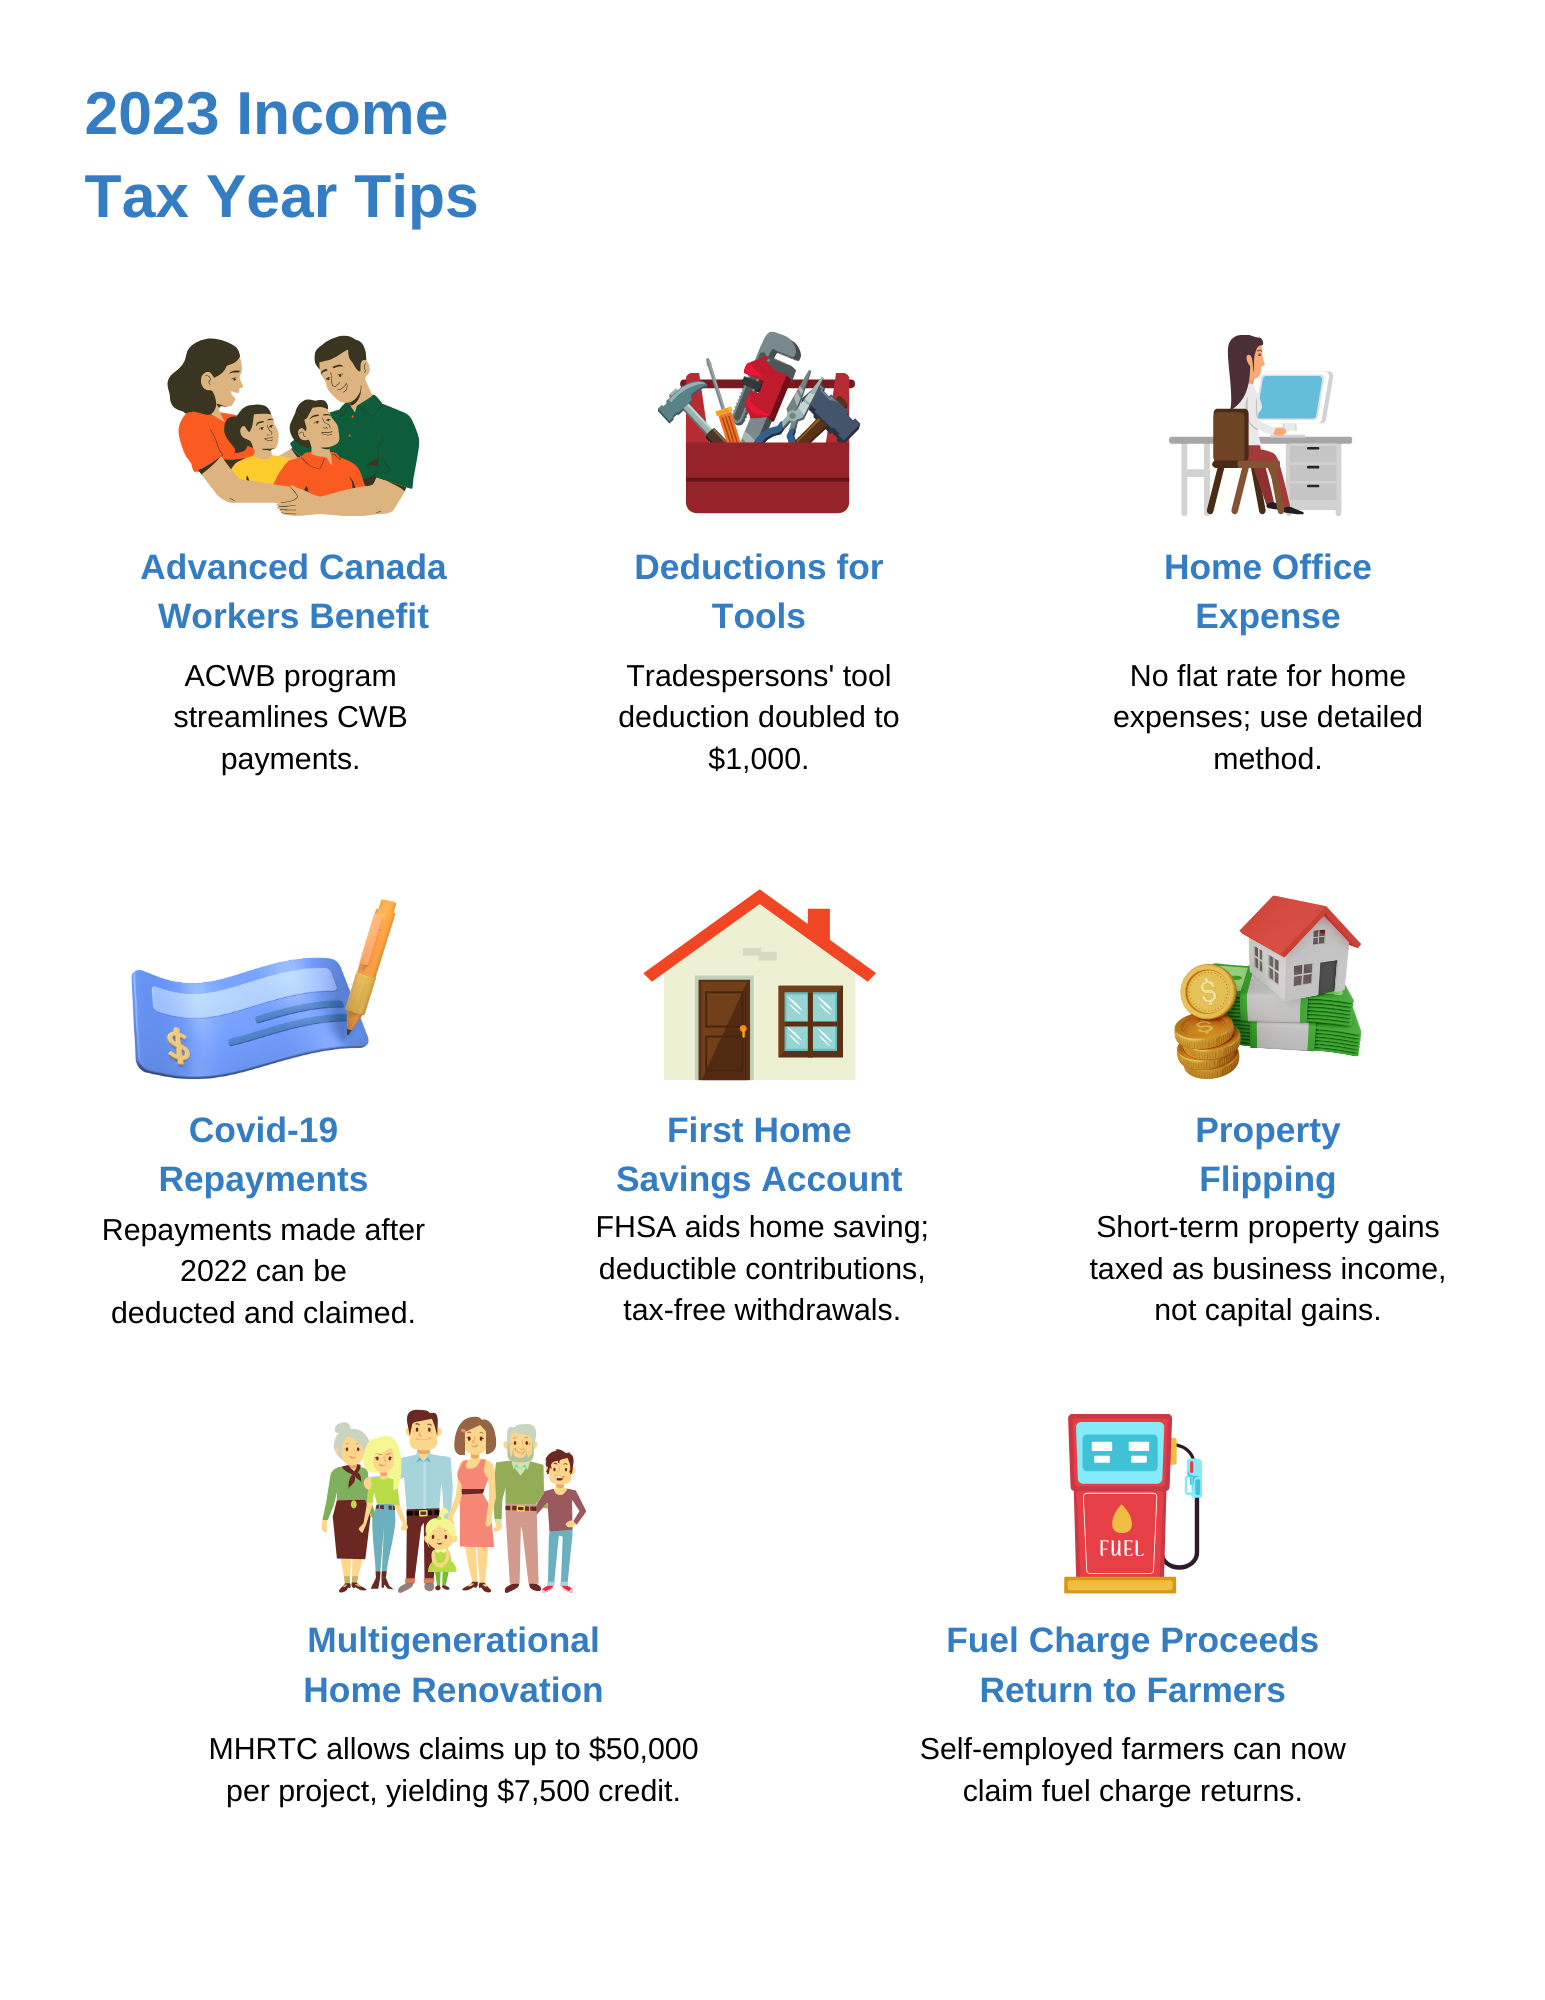
This year’s tax deadline is April 30, 2024. It’s important to make sure you’re claiming all the credits and deductions you’re eligible for. We’ve separated this article into 2 sections:
What’s new for 2023
Individuals and Families
Advanced Canada Workers Benefit (ACWB)
Automatic advance payments of the Canada Workers Benefit (CWB) are now seamlessly distributed through the ACWB program to individuals who received the benefit in the last tax year. However, it’s important to note that not everyone who received the CWB in the previous tax year will automatically receive the ACWB payments. Only individuals who filed their 2022 tax return before November 1, 2023, are eligible for the ACWB payments.
Furthermore, it’s worth mentioning that the ACWB program eliminates the need to file Form RC201. Recipients are no longer required to fill out this form. Instead, starting in 2023, individuals should report the amounts from their RC210 slip on Schedule 6, Canada Workers Benefit, of their tax return. Additionally, for eligible spouses, the option to claim the basic amount for the CWB is available regardless of who received the RC210 slip.
Deduction for Tools (Tradespersons and Apprentice Mechanics)
Starting in 2023, the maximum employment deduction for eligible tools of tradespersons has risen from $500 to $1,000. Consequently, the threshold for expenses eligible for the apprentice mechanics tools deduction has also been adjusted.
Temporary Flat Rate Method for Home Office Expenses
For the year 2023, the temporary flat rate method for claiming home office expenses is not applicable. Consequently, taxpayers seeking to claim such expenses for 2023 must utilize the detailed method and obtain a completed Form T2200, Declaration of Conditions of Employment, from their employer.
Federal, Provincial, and Territorial COVID-19 repayments
Repayments of COVID-19 benefits at the federal, provincial, and territorial levels, made after December 31, 2022, can be deducted and claimed.
First Home Savings Account (FHSA)
The FHSA is a registered plan designed to aid individuals in saving for their first home. Starting April 1, 2023, contributions made to an FHSA are typically deductible, and eligible withdrawals made from an FHSA for purchasing a qualifying home are tax-free.
Property Flipping
Starting January 1, 2023, any profit generated from the sale of a housing unit (including rental properties) situated in Canada, or a right to acquire a housing unit in Canada, that you owned or held for less than 365 consecutive days prior to its sale is considered business income rather than a capital gain. This is applicable unless the property was already classified as inventory or the sale occurred due to, or in anticipation of specific life events.
Multigenerational Home Renovation Tax Credit (MHRTC)
The MHRTC is a refundable tax credit designed to enable eligible individuals to seek reimbursement for specific renovation expenses incurred in establishing a secondary unit within an eligible dwelling. This enables a qualifying individual to live with their qualifying relative. If eligible, you can claim up to $50,000 in qualifying expenditures for each renovation project completed, with a maximum credit of $7,500 for each eligible claim.
Fuel Charge Proceeds Return to Farmers Tax Credit
The Fuel Charge Proceeds Return to Farmers Tax Credit is now accessible to self-employed farmers and individuals involved in a partnership operating a farming business with one or more permanent establishments located in Alberta, Manitoba, New Brunswick, Newfoundland and Labrador, Nova Scotia, Ontario, Prince Edward Island, or Saskatchewan. If eligible, you may be entitled to a refund of a portion of your fuel charge proceeds.
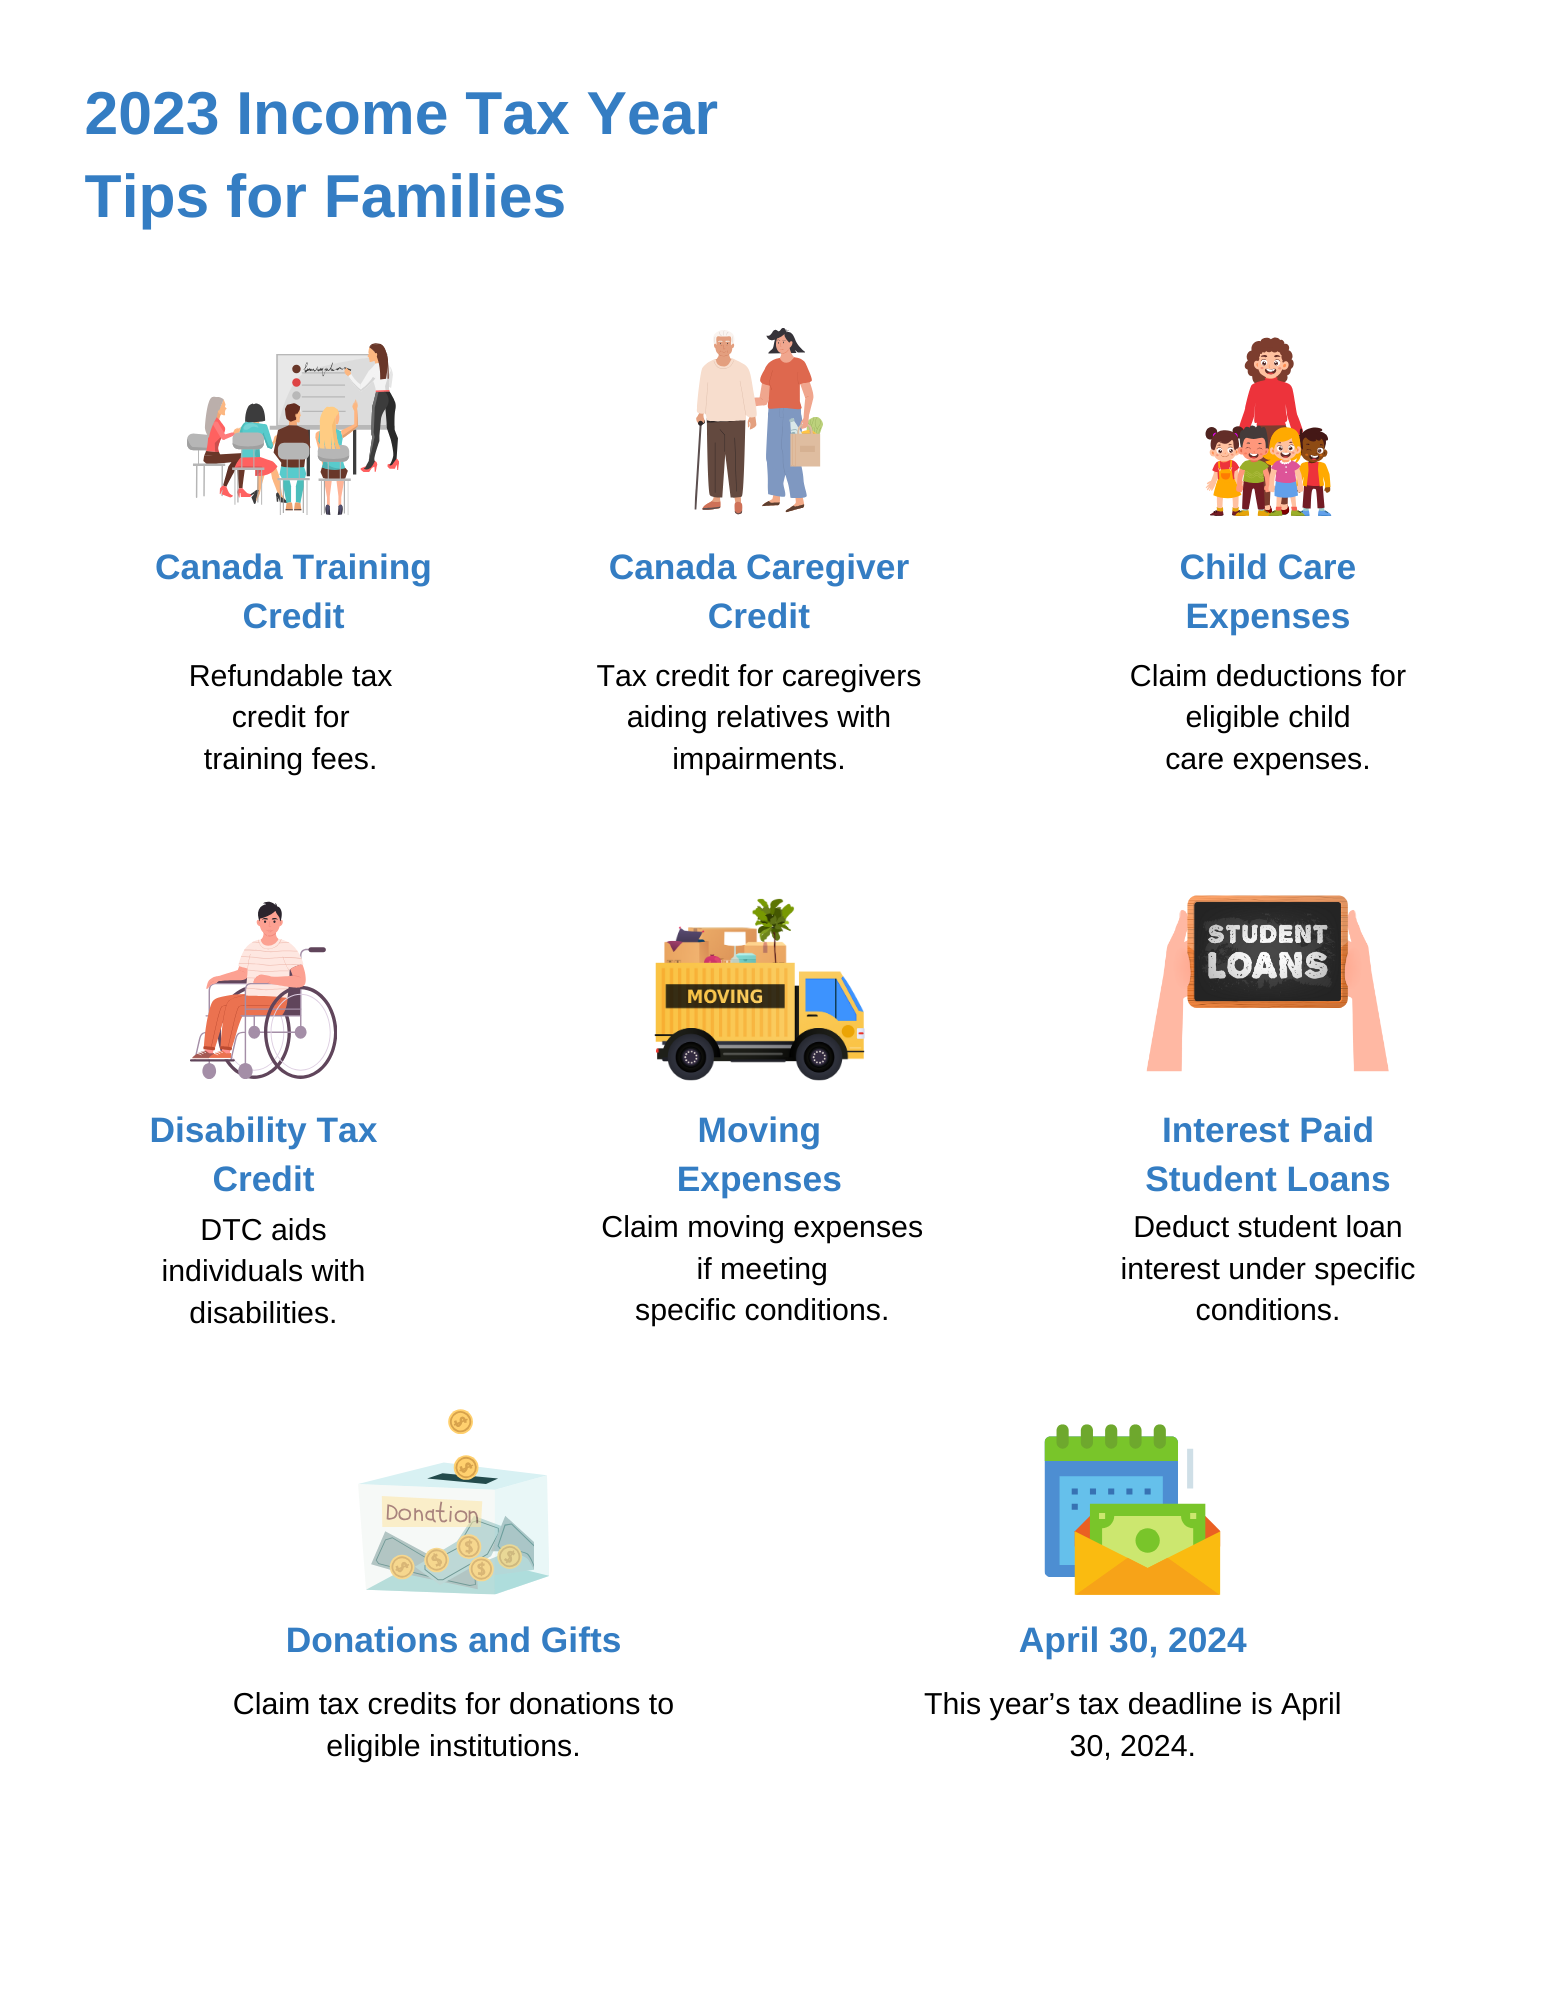
Canada Training Credit (CTC)
The CTC is a refundable tax credit available to help Canadians with the cost of eligible training fees.
To qualify for the CTC, you need to fill out Schedule 11 for the following:
Tuition fees and other applicable fees paid to an eligible educational institution in Canada for courses taken in 2023.
Fees paid to specific organizations for occupational, trade, or professional examinations undertaken in 2023.
To be eligible for the CTC, you must meet all these conditions:
You resided in Canada for the entire year of 2023.
You were at least 26 years old but less than 66 years old at the end of the year.
Your most recent notice of assessment or reassessment for 2022 shows a Canada Training Credit Limit for 2023.
Canada Caregiver Credit (CCC)
The CCC is a non-refundable tax credit aimed at assisting individuals who provide support to a spouse, common-law partner, or dependent with a physical or mental impairment, as outlined by the CRA.
You might be eligible for the CCC if you aid:
Your spouse or common-law partner dealing with a physical or mental impairment.
Dependents such as children, grandchildren, parents, grandparents, siblings, uncles, aunts, nieces, or nephews residing in Canada, who rely on you for consistent provision of basic needs like food, shelter, and clothing.
The amount you can claim varies depending on your relationship to the individual, your circumstances, their net income, and whether other credits are claimed for them.
Child Care Expenses
Child care expenses encompass payments made by you or someone else to arrange care for an eligible child. This care allows you to participate in income-earning activities, pursue education, or conduct research funded by a grant.
If you qualify, you can claim certain childcare expenses as deductions when you file your personal income tax return.
Disability Tax Credit (DTC)
The DTC is a non-refundable tax credit designed to support individuals with disabilities, or their family members who provide support, by reducing their income tax responsibilities.
To be eligible for this credit, individuals must have a significant and enduring impairment. Once approved, they can apply the credit when filing their taxes.
The DTC aims to ease some of the extra costs linked with the disability by lessening the individual’s income tax burden.
Moving
You can claim moving expenses you paid during the year if you meet these conditions
You moved to a new residence for work reasons, to start a business in a different area, or to attend a post-secondary program as a full-time student at a university, college, or other educational institution.
Your new residence must be at least 40 kilometres closer, determined by the shortest public route, to your new work location or educational institution.
Interest Paid on Student Loans
You might qualify to claim an amount for the interest paid on your student loan for post-secondary education if it was obtained under the following acts:
Canada Student Loans Act
Canada Student Financial Assistance Act
Apprentice Loans Act
Provincial or territorial government laws that are similar to the aforementioned acts.
Only you, or a person related to you, can claim the interest paid on the loan within the tax year 2023 or the preceding 5 years.
Donations and Gifts
When you or your spouse/common-law partner donate to eligible institutions, you might be eligible for federal and provincial/territorial non-refundable tax credits when you file your income tax and benefit return.
Normally, you can claim a portion or the full eligible donation amount, capped at 75% of your net income for the tax year.
Seeking guidance?
Wondering if you qualify for valuable tax credits or deductions? Reach out to us – as your financial advisor, we’re here to assist you in optimizing your finances and maximizing your savings.
Canada Training Credit: https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/about-your-tax-return/tax-return/completing-a-tax-return/deductions-credits-expenses/line-45350-canada-training-credit.html
Canada Caregiver Credit: https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/about-your-tax-return/tax-return/completing-a-tax-return/deductions-credits-expenses/canada-caregiver-amount.html
Disability Tax Credit: https://www.canada.ca/en/revenue-agency/services/tax/individuals/segments/tax-credits-deductions-persons-disabilities/disability-tax-credit.html
Interest Paid on Student Loans: https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/about-your-tax-return/tax-return/completing-a-tax-return/deductions-credits-expenses/line-31900-interest-paid-on-your-student-loans.html
Donations and Gifts: https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/about-your-tax-return/tax-return/completing-a-tax-return/deductions-credits-expenses/line-34900-donations-gifts.html
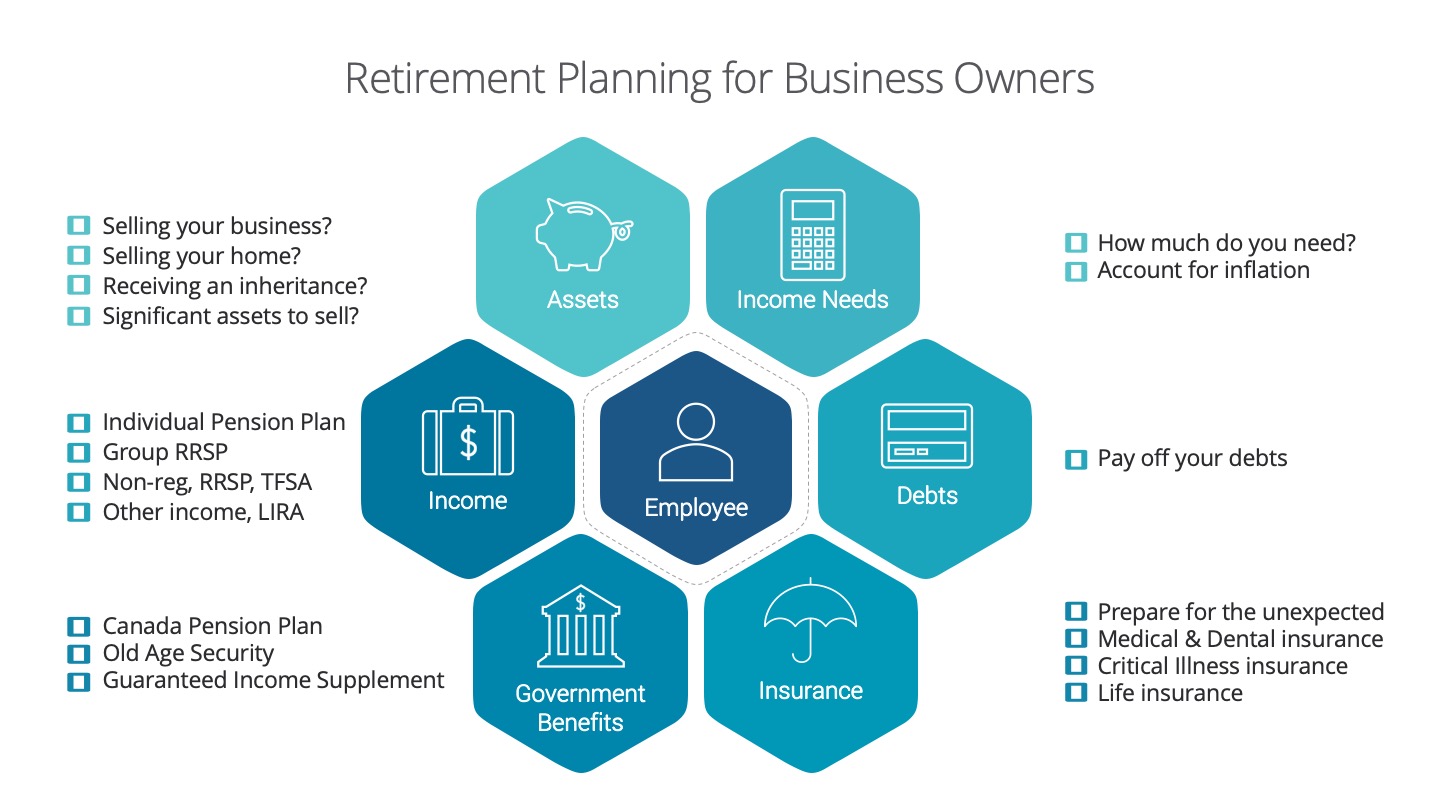
As a business owner, one of your challenges is learning how to balance between reinvesting into the business and setting money aside for personal savings. Since there are no longer employer-sponsored pension plans and the knowledge that retirement will come eventually, it’s important to have a retirement plan in place.
We’ve put together an infographic checklist that can help you get started on this. We know this can be a difficult conversation so we’re here to help and provide guidance to help you achieve your retirement dreams.
Income Needs
Determine how much income you will need in retirement.
Make sure you account for inflation in your calculations.
Debts
You should try to pay off your debts as soon as you can; preferably before you retire.
Insurance
As you age, your insurance needs change. Review your insurance needs, in particular your medical and dental insurance because a lot of plans do not provide health plans to retirees.
Review your life insurance coverage because you may not necessarily need as much life insurance as when you had dependents and a mortgage, but you may still need to review your estate and final expense needs.
Prepare for the unexpected such as a critical illness or a need for long-term care.
Government Benefits
Check what benefits are available for you upon retirement.
Canada Pension Plan- decide when would be the ideal time to apply and receive CPP payments. Business owners are in a unique position to control how much can be contributed to CPP by deciding to pay salary or dividends. (Dividends don’t trigger CPP contributions.)
Old Age Security- check pension amounts and see if there’s a possibility of clawback.
Guaranteed Income Supplement- if your income is low enough, you could apply for GIS.
Income
Are you a candidate for an individual pension plan (IPP)? IPPs can provide higher contributions than typically permitted to an RRSP and the ability to create a lifelong pension.
Check if your business is a candidate for a group RRSP or company pension plan. This is a great way for you to build retirement savings and provide benefits for your employees and business too.
Make sure you are saving on a regular basis towards retirement- in an RRSP, TFSA, or non-registered account. As you can control how you get paid, you should make sure you have the optimal mix of salary and dividends to achieve your financial goals. Dividends are not considered eligible income to create RRSP room.
Ensure your investment mix makes sense for your situation.
Don’t forget to check if there are any other income sources. (e.g. rental income, side hustle income, etc.)
Assets
The sale of your business can be part of your retirement nest egg. Therefore, you should make sure you know the valuation of your business and your plan to sell the business to your family, employees, partners or a third party. You should also know when you decide to sell your business.
Are you planning to use the sale of your home or other assets to fund your retirement?
Will you be receiving an inheritance?
One other consideration that’s not included in the checklist is divorce. This can be an uncomfortable question; however, divorce amongst adults ages 50 and over is on the rise and this can be financially devastating for both parties.
Contact us about helping you get your retirement planning in order so your retirement dreams can be achieved.
You have worked long and hard to build up your business, and now you are ready to withdraw money from your business’ bank account. But you don’t want to get hit with a huge tax bill. So here are 5 ways to withdraw money from your business in a tax-efficient manner.
1) Pay Yourself And Your Family Members
You can pay yourself a salary from your business and pay any family members who work in your business. However, the salary you pay family members must not be excessive – it must be in line with what they would receive for doing the same work elsewhere.
You and your family members will be taxed at the regular personal marginal tax rates on your salaries. However, your corporation can make a deduction based on salaries paid when determining taxable income.
2) Pay Out Taxable Dividends
You can use dividends to distribute money from your corporation to both yourself and family members if everyone holds shares in your corporation. However, when distributing dividends to a shareholder, it is critical to consider both the tax on split income (TOSI) rules and the corporate attribution rules before any distribution is made.
TOSI rules – Under the current income tax rules, the TOSI applies the highest marginal tax rate (currently 33%) to “split income” of an individual under the age of 18. In general, an individual’s split income includes certain taxable dividends, taxable capital gains and income from partnerships or trusts. – Canada.ca
Corporate attribution rules – Corporate attribution rules may result in additional tax if a transfer or loan to a corporation is made to shift income to another family member. This can result in additional tax for the individual making the transfer or loan.
3) Pay Out Capital Dividends
Another way to pay out dividends is via your corporation’s capital dividend account (CDA). Money in your corporation’s CDA can be dispersed to Canadian resident shareholders as a tax-free dividend, but be sure you are clear on what can legally be allowed in your CDA before you do this.
4) Adjust Your Salary And Dividend Mix
Keeping the right mix when paying yourself a salary and paying yourself via dividends is essential. You need to consider various factors – such as your cash flow needs, earned income for RRSP contributions, and any impact on taxes and other regulatory requirements – paying out salaries and dividends can have.
5) Repay Any Outstanding Shareholder Loans
If you loaned money to your company in the form of a shareholder loan, now may be the time to have your company repay that loan. Any money you receive to settle your shareholder loan will be paid to you as a tax-free distribution.
The Takeaway
Regardless of why you need to take cash out of your business, it is crucial to plan how to withdraw the money so you can do it in the most tax-efficient manner possible. Unfortunately, there is no one-size-fits-all solution for this, which is why talking to a professional advisor is so important.
We can help design a tax-optimized compensation strategy for you. Contact us to set up a meeting today!
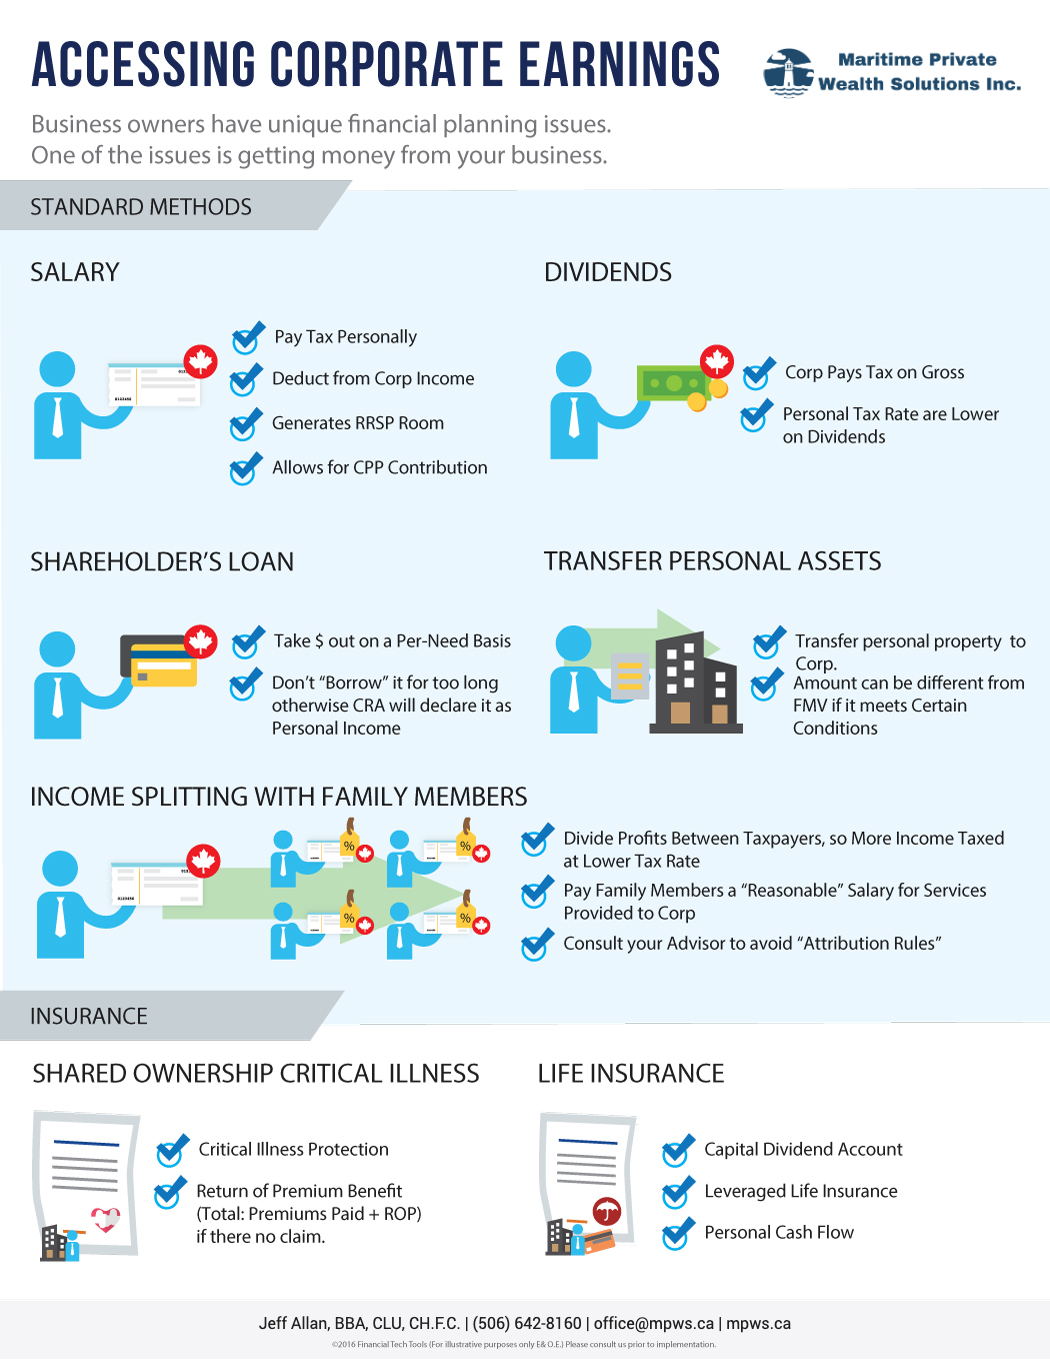
One of the financial planning issues that business owners face is how to access their corporate earnings in a tax efficient way.
There are 5 standard methods:
Salary
Dividend
Shareholder Loans
Transfer Personal Assets
Income Splitting
There are also unique ways utilizing life insurance and critical illness insurance to access your retained earnings. Please contact us to learn how we can get more money in your pocket than in the government’s.
As a business owner, one of your challenges is learning how to balance between reinvesting into the business and setting money aside for personal savings. Since there are no longer employer-sponsored pension plans and the knowledge that retirement will come eventually, it’s important to have a retirement plan in place.
We’ve put together an infographic checklist that can help you get started on this. We know this can be a difficult conversation so we’re here to help and provide guidance to help you achieve your retirement dreams.
Income Needs
Determine how much income you will need in retirement.
Make sure you account for inflation in your calculations.
Debts
You should try to pay off your debts as soon as you can; preferably before you retire.
Insurance
As you age, your insurance needs change. Review your insurance needs, in particular your medical and dental insurance because a lot of plans do not provide health plans to retirees.
Review your life insurance coverage because you may not necessarily need as much life insurance as when you had dependents and a mortgage, but you may still need to review your estate and final expense needs.
Prepare for the unexpected such as a critical illness or a need for long-term care.
Government Benefits
Check what benefits are available for you upon retirement.
Canada Pension Plan- decide when would be the ideal time to apply and receive CPP payments. Business owners are in a unique position to control how much can be contributed to CPP by deciding to pay salary or dividends. (Dividends don’t trigger CPP contributions.)
Old Age Security- check pension amounts and see if there’s a possibility of clawback.
Guaranteed Income Supplement- if your income is low enough, you could apply for GIS.
Income
Are you a candidate for an individual pension plan (IPP)? IPPs can provide higher contributions than typically permitted to an RRSP and the ability to create a lifelong pension.
Check if your business is a candidate for a group RRSP or company pension plan. This is a great way for you to build retirement savings and provide benefits for your employees and business too.
Make sure you are saving on a regular basis towards retirement- in an RRSP, TFSA, or non-registered. Since you can control how you get paid, salary or dividends, dividends are not considered eligible income to create RRSP room, therefore you should make sure you have the optimal mix of both to achieve your financial goals.
Ensure your investment mix makes sense for your situation.
Don’t forget to check if there are any other income sources. (ex. rental income, side hustle income, etc.)
Assets
The sale of your business can be part of your retirement nest egg. Therefore, you should make sure you know the valuation of your business and your plan to sell the business to your family, employees, partners or a third party. You should also know when you decide to sell your business too.
Are you planning to use the sale of your home or other assets to fund your retirement?
Will you be receiving an inheritance?
One other consideration that’s not included in the checklist is divorce. This can be an uncomfortable question, however divorce amongst adults ages 50 and over is on the rise and this can be financially devastating for both parties.
Contact Us about helping you get your retirement planning in order so your retirement dreams can be achieved.

Now that we’re approaching the end of the year, it’s time to review your business finances. We’ve highlighted the most critical tax-planning tips you need to know as a business owner.
Salary and Dividend Mix
As a business owner, one essential part of tax planning is determining the right mix of salary and dividends for both yourself and your family members.
The following are the main options you can consider when determining how to distribute money from your business:
Pay a salary to family members who work for your business and are in a lower tax bracket – This enables them to declare an income so that they can contribute to the Canada Pension Plan (CPP) and a Registered Retirement Savings Plan (RRSP). You must be able to prove the family members have provided services in line with the amount of compensation provided.
Pay dividends to family members who are shareholders in your company – The amount of dividends someone can receive without paying income tax on them will vary depending on the province or territory they live in.
Distribute money from your business via income sprinkling – This is shifting income from a high-tax rate individual to a low-rate tax individual. However, this strategy can cause issues due to Tax On Split Income (TOSI) rules. A tax professional can help you determine the best way to “income sprinkle” so none of your family members are subject to TOSI.
Keep money in the corporation if neither you nor your family members need cash – Taxes can be deferred if your corporation retains income and the corporation’s tax rate is lower than your personal tax rate.
No matter what strategy you take to distribute money from your business, keep in mind the following:
Your marginal tax rate as the owner-manager.
The corporation’s tax rate.
Health and payroll taxes.
How much RRSP contribution room do you have.
What you’ll have to pay in CPP contributions.
Other deductions and credits you’ll be eligible for (e.g., charitable donations or childcare or medical expenses).
Compensation
An important part of year-end tax planning is determining appropriate ways to handle compensation. The following are the main things to consider:
Can you benefit from a shareholder loan? A shareholder loan is an agreement to borrow funds from your corporation for a specific purpose. The interest from the loan may be deductible if the proceeds of the shareholder loan were used to produce income from business or property.
Do you need to repay a shareholder loan to avoid paying personal income tax on the amount you borrowed?
Is setting up an employee profit-sharing plan a better way to disburse business profits than simply paying out a bonus?
Keep in mind that when an employee cashes out a stock option, only one party (the employee OR the employer) can claim a tax deduction on the cashed-out stock option.
Think about setting up a Retirement Compensation Arrangement (RCA) to help fund you or your employee’s retirement.
Passive Investments
One of the most common tax advantages available to Canadian-Controlled Private Corporations (CCPC) is the Small Business Deduction (SBD).
For qualifying businesses, the SBD reduces your corporate tax rate. Keep in mind that the SBD will be reduced by five dollars for every dollar of passive investment income over $50,000 your CCPC earned the previous year.
The best way to avoid losing any of the SBD is to make sure that the passive investment income within your associated corporation group does not exceed $50,000.
These are some of the ways you can make sure you preserve your access to the SBD:
Defer the sale of portfolio investments as necessary.
Adjust your investment mix to be more tax efficient. For example, you could choose to hold more equity investments than fixed-income investments. Only 50% of the gains realized on shares sold is taxable, but investment income earned on bonds is fully taxable.
Invest excess funds in an exempt life insurance policy. Any investment income earned on an exempt life insurance policy is not included in your passive investment income total.
Set up an individual pension plan (IPP). An IPP is like a defined benefit pension plan and is not subject to the passive investment income rules.
Depreciable Assets
Another tactic you should consider for year-end tax planning is to hasten your purchase of any depreciable assets. A depreciable asset is a type of capital property that you can claim the Capital Cost Allowance (CCA) on.
These are two of the best ways to make the most of tax planning with depreciable assets:
Make use of the Accelerated Investment Incentive. With this incentive, some depreciable assets are eligible for an enhanced first-year allowance.
Purchase equipment such as zero-emissions vehicles and clean energy equipment eligible for a 100 percent tax write-off.
Donations
Another essential part of tax planning is to make all of your donations before year-end. This applies to both charitable donations and political contributions.
For charitable donations, you need to consider the best way to make your donations and the different tax advantages of each type of donation. For example, you can:
Donate securities.
Give a direct cash gift to a registered charity.
Use a donor-advised fund account at a public foundation. A donor-advised fund is like a charitable investment account.
Set up a private foundation to solely represent your interests.
We can help walk you through the tax implications of each of these types of charitable donations.
Make the Most of Covid-19 Relief Programs
While some COVID-19 relief programs, such as the Canada Emergency Wage Subsidy (CEWS) and Canada Emergency Rent Subsidy (CERS) have ended, others are still available. See if your business can benefit from any of the following relief programs:
Canada Recovery Hiring Program (CRHP). This program will continue to run until May 2022. If your business is eligible and continues to experience a decline in revenues as compared to pre-pandemic levels. In that case, the CRHP will provide support to assist in hiring new staff or increasing the wages of your existing staff.
Tourism and Hospitality Recovery Program. This new program provides wage and rent support to eligible businesses such as hotels and restaurants with an average monthly revenue reduction of at least 40% over the first 13 qualifying periods for the CEWS and a current month revenue loss of at least 40%.
Hardest Hit Business Recovery Program. This provides rent and wage support of up to 50% for eligible entities. Eligible entities must meet two conditions – an average monthly revenue reduction of at least 50% over the first 13 qualifying periods for the CEWS and a current month revenue loss of at least 50%.
General support in the event of a public health lockdown. If there is a public health lockdown and your business loses sufficient revenue, your business would be eligible for support at the same subsidy rates as the Tourism and Hospitality Recovery Program.
Know what’s included as taxable income. If you received assistance from the government assistance programs, including the CEWS, CERS, and CRHP, this assistance is taxable as income.
Get year-end tax planning help from someone you can trust!
We’re here to help you with your year-end tax planning. Book some time with us today to learn how you can benefit from these tax tips and strategies.
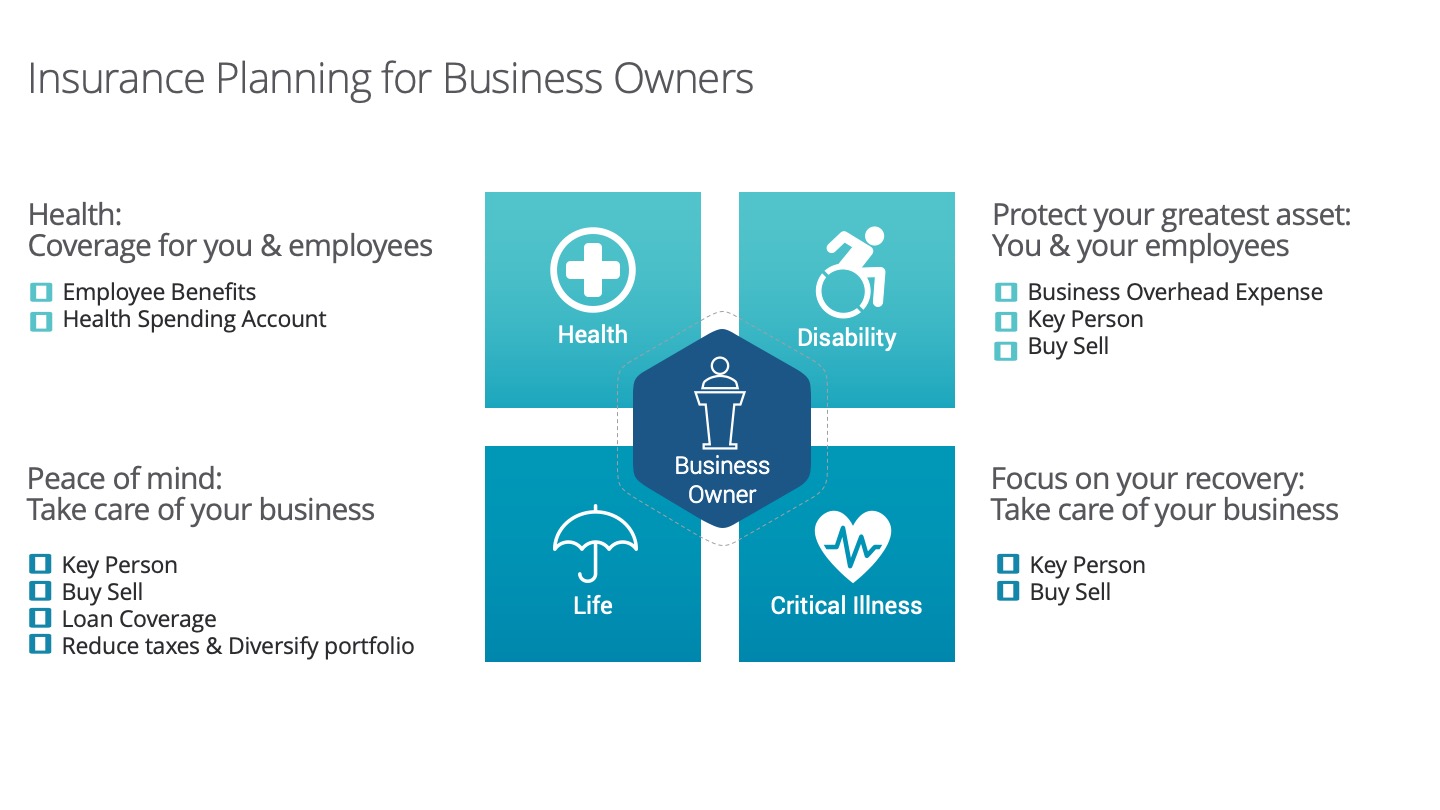
For business owners, making sure your business is financially protected can be overwhelming. Business owners face a unique set of challenges when it comes to managing risk. Insurance can play an important role when it comes to reducing the financial impact on your business in the case of uncontrollable events such as disability, critical illness or loss of a key shareholder or employee.
This infographic addresses the importance of corporate insurance.
The 4 areas of insurance a business owner should take care of are:
Health
Disability
Critical Illness
Life
Health: We are fortunate in Canada, where the healthcare system pays for basic healthcare services for Canadian citizens and permanent residents. However, not everything healthcare related is covered, in reality, 30% of our health costs* are paid for out of pocket or through private insurance such as prescription medication, dental, prescription glasses, physiotherapy, etc.
For business owners, offering employee health benefits make smart business sense because health benefits can form part of a compensation package and can help retain key employees and attract new talent.
For business owners that are looking to provide alternative health plans in a cost effective manner, you may want to consider a health spending account.
Disability: Most people spend money on protecting their home and car, but many overlook protecting their greatest asset: their ability to earn income. Unfortunately one in three people on average will be disabled for 90 days or more at least once before the age of 65.
Consider the financial impact this would have on your business if you, a key employee or shareholder were to suffer from an injury or illness. Disability insurance can provide a monthly income to help keep your business running.
Business overhead expense insurance can provide monthly reimbursement of expenses during total disability such as rent for commercial space, utilities, employee salaries and benefits, equipment leasing costs, accounting fees, insurance premiums for property and liability, etc.
Key person disability insurance can be used to provide monthly funds for the key employee while they’re disabled and protect the business from lost revenue while your business finds and trains an appropriate replacement.
Buy sell disability insurance can provide you with a lump sum payment if your business partner were to become totally disabled. These funds can be used to purchase the shares of the disabled partner, fund a buy sell agreement and reassure creditors and suppliers.
Critical Illness: For a lot of us, the idea of experiencing a critical illness such as a heart attack, stroke or cancer can seem unlikely, but almost 3 in 4 (73%) working Canadians know someone who experience a serious illness. Sadly, this can have serious consequences on you, your family and business, with Critical Illness insurance, it provides a lump sum payment so you can focus on your recovery.
Key person critical illness insurance can be used to provide funds to the company so it can supplement income during time away, cover debt repayment, salary for key employees or fixed overhead expenses.
Buy sell critical illness insurance can provide you with a lump sum payment if your business partner or shareholder were to suffer from a critical illness. These funds can be used to purchase the shares of the partner, fund a buy sell agreement and reassure creditors and suppliers.
Life: For a business owner, not only do your employees depend on you for financial support but your loved ones do too. Life insurance is important because it can protect your business and also be another form of investment for excess company funds.
Key person life insurance can be used to provide a lump sum payment to the company on death of the insured so it can keep the business going until you an appropriate replacement is found. It can also be used to retain loyal employees by supplying a retirement fund inside the insurance policy.
Buy sell life insurance can provide you with a lump sum payment if your business partner or shareholder were to pass away. These funds can be used to purchase the shares of the deceased partner, fund a buy sell agreement and reassure creditors and suppliers.
Loan coverage life insurance can help cover off any outstanding business loans and debts.
Reduce taxes & diversify your portfolio, often life insurance is viewed only as protection, however with permanent life insurance, there is an option to deposit excess company funds not needed for operations to provide for tax-free growth (within government limits) to diversify your portfolio and reduce taxes on passive investments.
Talk to us about helping making sure you and your business are protected.
On April 19, 2021, the Federal Government released their 2021 budget. We have broken down the highlights of the financial measures in this budget into three different sections:
Business Owners
Personal Tax Changes
Supplementary Highlights
All of the following COVID-19 Emergency Business Supports will be extended from June 5, 2021, to September 25, 2021, with the subsidy rates gradually decreasing:
Canada Emergency Wage Subsidy (CEWS) – The maximum wage subsidy is currently 75%. It will decrease down to 60% for July, 40% for August, and 20% for September.
Canada Emergency Rent Subsidy (CERS) – The maximum rent subsidy is currently 65%. It will decrease down to 60% for July, 40% for August, and 20% for September.
Lockdown Support Program – The Lockdown Support Program rate of 25% will be extended from June 4, 2021, to September 25, 2021.
Only organizations with a decline in revenues of more than 10% will be eligible for these programs as of July 4, 2021. The budget also includes legislation to give the federal government authority to extend these programs to November 20, 2021, should either the economy or the public health situation make it necessary.
The federal budget introduced a new program called the Canada Recovery Hiring Program. The goal of this program is to help qualifying employers offset costs taken on as they reopen. An eligible employer can claim either the CEWS or the new subsidy, but not both.
The proposed subsidy will be available from June 6, 2021, to November 20, 2021, with a subsidy of 50% available from June to August. The Canada Recovery Hiring Program subsidy will decrease down to 40% for September, 30% for October, and 20% for November.
The federal budget for 2021 introduces new interest deductibility limits. This rule limits the amount of net interest expense that a corporation can deduct when determining its taxable income. The amount will be limited to a fixed ratio of its earnings before interest, taxes, depreciation, and amortization (sometimes referred to as EBITDA).
The fixed ratio will apply to both existing and new borrowings and will be phased in at 40% as of January 1, 2023, and 30% for January 1, 2024.
The federal budget also includes 4 billion dollars to help small and medium-sized businesses innovate by digitizing and taking advantage of e-commerce opportunities. Also, the budget provides additional funding for venture capital start-ups via the Venture Capital Catalyst Program and research that will support up to 2,500 innovative small and medium-sized firms.
The federal budget includes information on both the tax treatment and repayment of the following COVID-19 benefits:
Canada Emergency Response Benefits or Employment Insurance Emergency Response Benefits
Canada Emergency Student Benefits
Canada Recovery Benefits, Canada Recovery Sickness Benefits, and Canada Recovery Caregiving Benefits
Individuals who must repay a COVID-19 benefit amount can claim a deduction for that repayment in the year they received the benefit (by requesting an adjustment to their tax return), not the year they repaid it. Anyone considered a non-resident for income tax purposes will have their COVID-19 benefits included in their taxable income.
Eligibility changes have been made to the Disability Tax Credit. The criteria have been modified to increase the list of mental functions considered necessary for everyday life, expand the list of what can be considered when calculating time spent on therapy, and reduce the requirement that therapy is administered at least three times each week to two times a week (with the 14 hours per week requirement remaining the same).
The budget enhances Old Age Security (OAS) benefits for recipients who will be 75 or older as of June 2022. A one-time, lump-sum payment of $500 will be sent out to qualifying pensioners in August 2021, with a 10% increase to ongoing OAS payments starting on July 1, 2022.
The budget also notes that the government plans to introduce legislation that will extend waiving of any interest accrued on either Canada Student Loans or Canada Apprentice Loans until March 31, 2023.
Support to help Canadians transition to growing industries was also included in the budget. The support is as follows:
$250 million over three years to Innovation, Science and Economic Development Canada to help workers upskill and redeploy to growing industries.
$298 million over three years for the Skills for Success Program to provide training in skills for the knowledge economy.
$960 million over three years for the Sectoral Workforce Solutions Program to help design and deliver training relevant to the needs of small and medium businesses.
The federal budget also introduces a proposed federal minimum wage of $15 per hour that would rise with inflation.
The GST New Housing Rebate conditions will be changed. Previously, if two or more individuals were buying a house together, all of them must be acquiring the home as their primary residence (or that of a relation) to qualify for the GST New Housing Rebate. Now, the GST New Housing Rebate will be available as long as one of the purchasers (or a relation of theirs) acquires the home as their primary place of residence. This will apply to all agreements of purchase and sale entered into after April 19, 2021.
A new tax was introduced in the budget on unproductive use of Canadian housing by non-resident foreign owners. This tax will be a 1% tax on the value of non-resident, non-Canadian owned residential real estate considered vacant or underused. This tax will be levied annually starting in 2022.
All residential property owners in Canada (other than Canadian citizens or permanent residents of Canada) must also file an annual declaration for the prior calendar year with the CRA for each Canadian residential property they own, starting in 2023. Filing the annual declaration may qualify owners to claim an exemption from the tax on their property if they can prove the property is leased to qualified tenants for a minimum period in a calendar year.
The budget also includes a new proposal on excise duties on vaping products and tobacco. The proposed framework would consist of:
A single flat rate duty on every 10 millilitres of vaping liquid as of 2022
An increase in tobacco excise duties by $4 per carton of 200 cigarettes and increases to the excise duty rates for other tobacco products such as tobacco sticks and cigars as of April 20, 2021.
Finally, the federal budget proposed introducing a tax on certain luxury goods for personal use as of January 1, 2022.
For luxury cars and personal aircraft, the new tax is equal to the lesser of 10% of the vehicle’s total value or the aircraft, or 20% of the value above $100,000.
For boats over $250,000, the new tax is equal to the lesser of 10% of the full value of the boat or 20% of the value above $250,000.
If you have any questions or concerns about how the new federal budget may impact you, call us – we’d be happy to help you!


