Why consider Critical Illness Insurance?
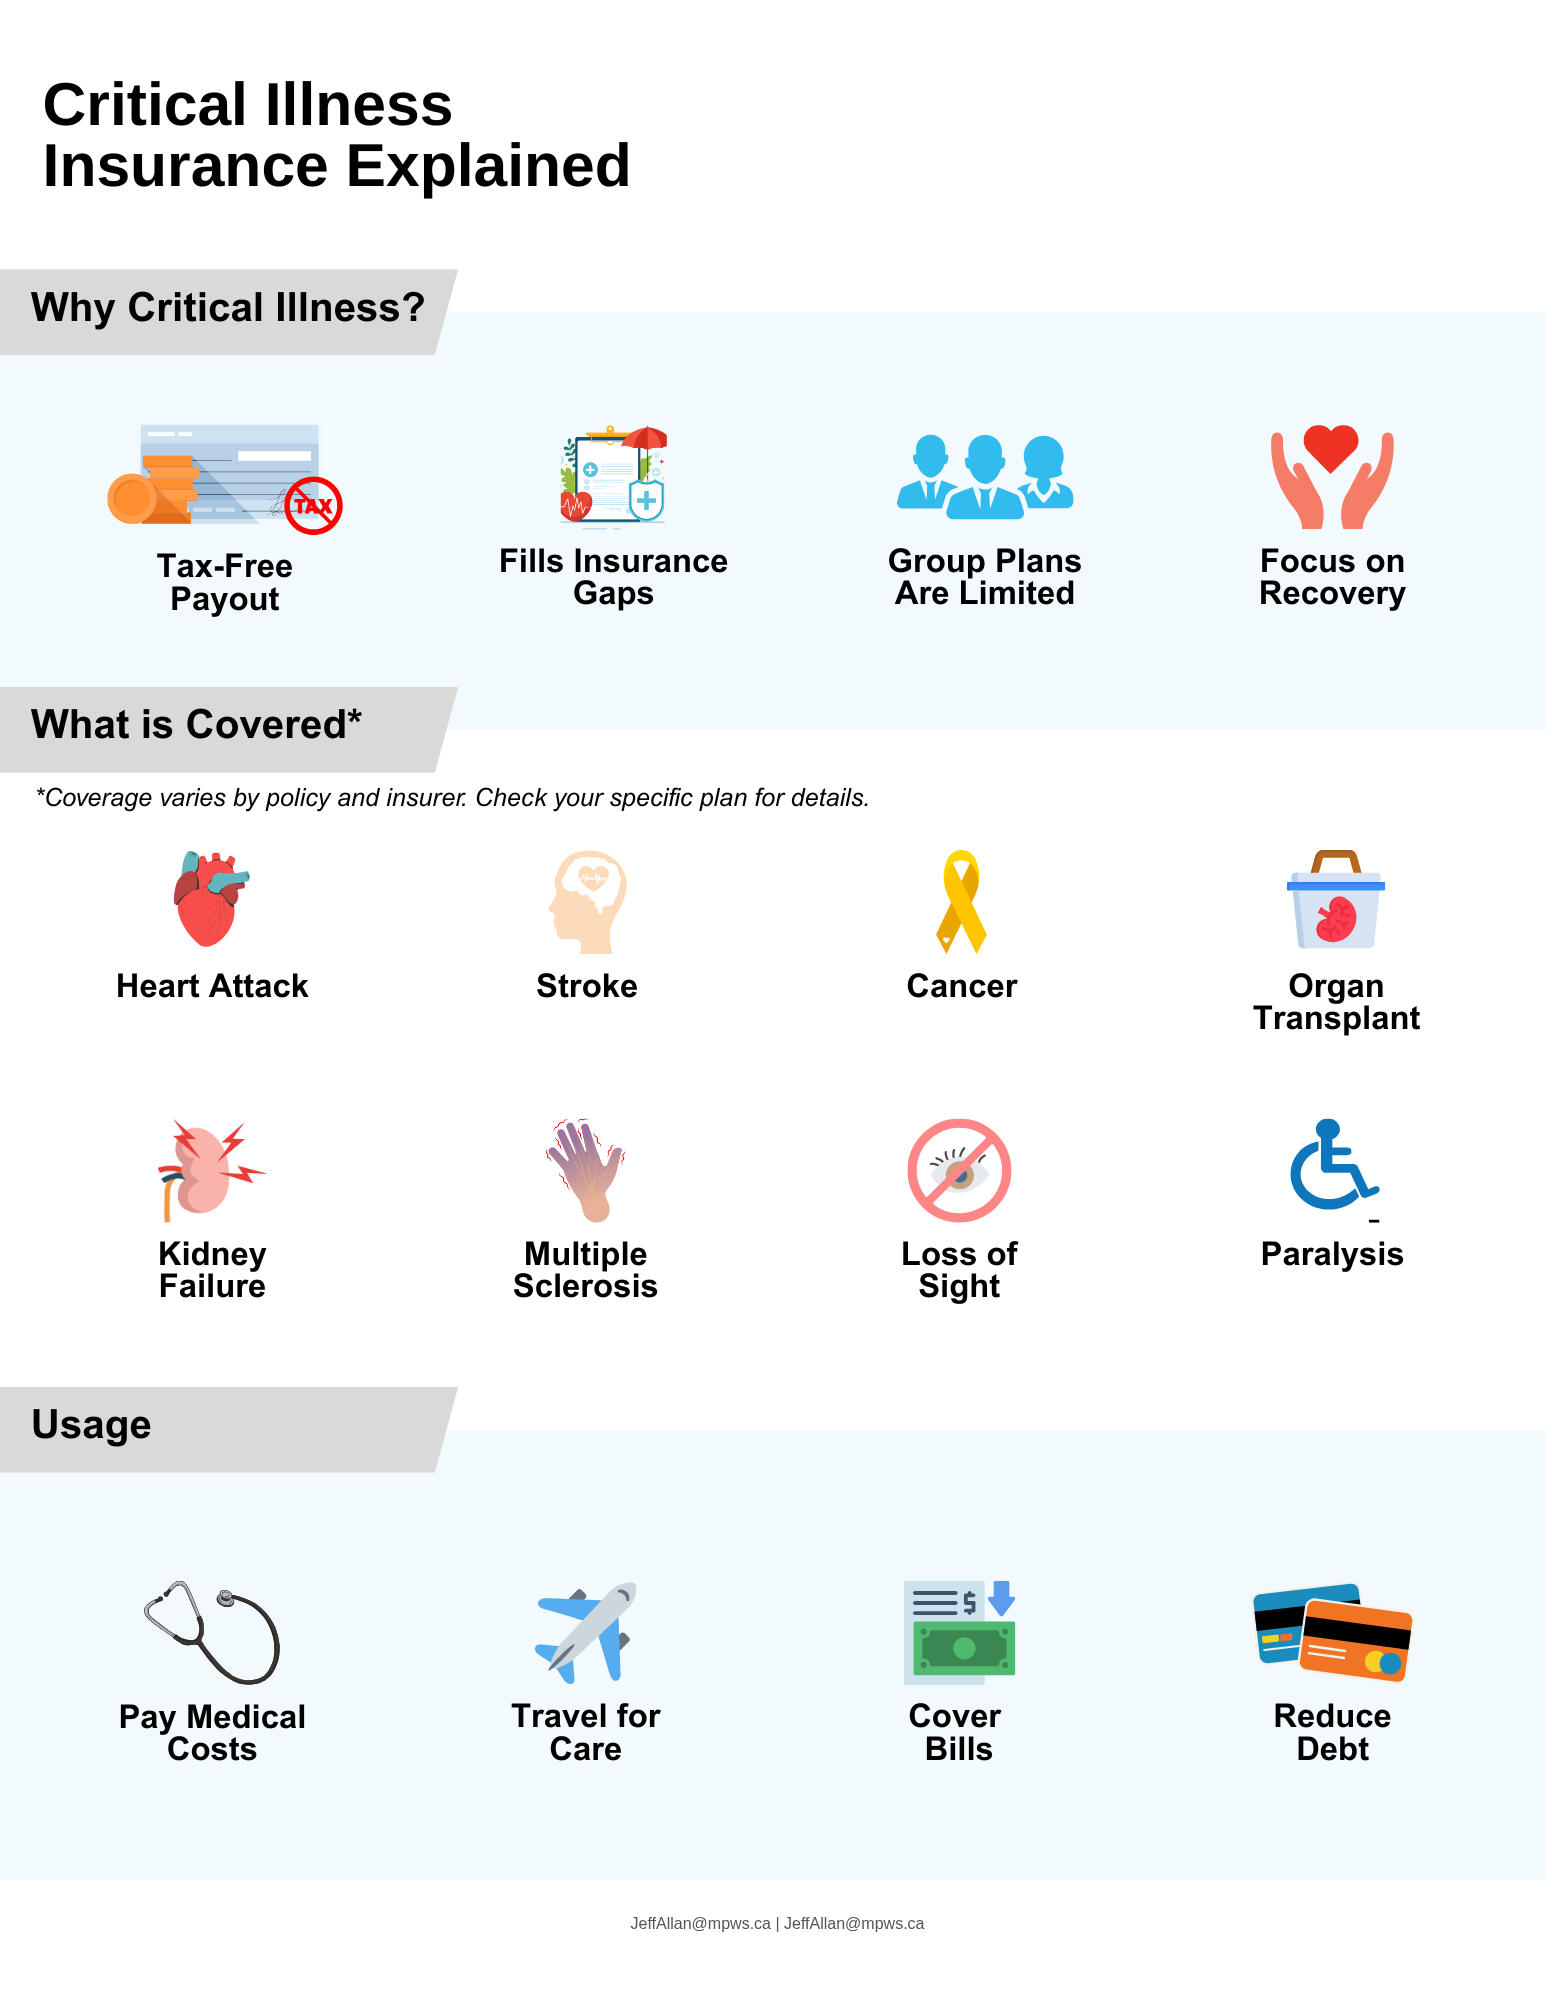
The purpose of Critical Illness Insurance is to provide a tax-free lump sum benefit if you’re diagnosed with a covered serious illness. It’s designed to ease the financial pressure that often comes with time away from work, medical costs not covered by government plans, and other unexpected expenses — so you can focus on your recovery, not your finances.
Even if you already have life insurance or workplace benefits, Critical Illness Insurance offers unique protection. Group plans often include only small amounts of coverage, may end if you leave your job, and usually don’t let you choose the benefit amount. A personal policy stays with you and can be tailored to your needs.
What does it cover?
Critical Illness Insurance pays out if you’re diagnosed with one of the serious medical conditions listed in your policy. These commonly include:
Some policies also provide partial payments for early-stage diagnoses. Your advisor can explain the specific definitions and conditions covered by your plan.
What types of policies are available?
Critical Illness Insurance is available in several forms, so you can choose the one that fits your needs and budget. The most common types include:
Is there a waiting period?
Yes — most policies include a short waiting period after diagnosis, usually 30 days, before the benefit is paid.
What factors affect the cost of Critical Illness Insurance?
The premium you pay for Critical Illness Insurance is influenced by both your personal situation and the policy you select. Understanding these factors can help you plan your coverage effectively:
By working with an advisor, you can balance these factors and find a policy that gives you the right level of protection at a price you’re comfortable with.
Are the benefits taxable?
No — in Canada, Critical Illness Insurance pays a tax-free lump sum benefit you can use however you wish.
How can you use the money?
The benefit is completely flexible. Many use it to:
When is the best time to purchase?
The best time to purchase Critical Illness Insurance is when you’re younger and healthy, so you qualify more easily and pay lower premiums.
How does Critical Illness Insurance fit into your insurance plan?
Most people already include life insurance in their plans to protect their family if they pass away. Many also rely on group disability insurance to replace part of their income if they can’t work due to illness or injury.
But Critical Illness Insurance is often overlooked — and that can leave a gap.
Life insurance only pays if you die, and disability insurance often replaces only a portion of your income, usually with limits and waiting periods. Neither addresses the immediate, unexpected costs of a serious illness, like out-of-pocket medical expenses, travel for treatment, hiring help at home, or paying off debts quickly.
Critical Illness Insurance fills this gap by providing a lump sum, tax-free benefit right after diagnosis, even if you’re still able to work. It complements your life and disability insurance to give you and your family a more complete, well-rounded safety net.
It’s worth reviewing your overall plan to make sure all three pieces — life, disability, and critical illness — are working together to protect your family and your lifestyle no matter what happens.
Critical Illness Insurance provides financial security during one of life’s most challenging times. It’s flexible, tax-free, and tailored to your needs — giving you and your family confidence that you’ll have support if the unexpected happens.
If you’d like help exploring your options or getting a personalized quote, reach out anytime.
If you’re a dentist in a partnership or group practice, having a clear buy-sell agreement isn’t just a good idea—it’s essential. A properly funded buy-sell agreement ensures your practice remains stable and your family, partners, and patients are protected in case of unexpected events like death, disability, or critical illness.
As a financial advisor who specializes in working with dentists, I help you put the right structure and funding in place so your dental practice can continue to thrive—even if life throws a curveball.
A buy-sell agreement is a legally binding contract between dental practice owners. It outlines what happens if a partner dies, becomes disabled, retires, or chooses to exit the practice.
When dentists don’t have a buy-sell agreement in place, it can lead to:
Disagreements with surviving family members
Loss of patients due to uncertainty
A forced or rushed sale of the practice
Financial strain on remaining partners
It’s not enough to have the agreement in writing—you need the money ready when it’s needed. That’s where insurance comes in. It’s the most efficient and cost-effective way to fund a buy-sell agreement for dentists.
Life Insurance: Provides a tax-free payout so surviving partners can buy out the deceased dentist’s share of the practice.
Disability Insurance: If a dentist becomes disabled, this policy provides funds to purchase their share, keeping the business running.
Critical Illness Insurance: Offers a lump sum in case of serious illness, allowing partners to buy out or restructure without financial stress.
Setting up a buy-sell agreement for dentists involves a team of professionals:
Financial Advisor –Provides funding strategies using life, disability, and critical illness insurance.
Accountant – Assesses practice value and tax impact
Lawyer – Drafts the legal agreement and aligns it with your business structure
As your advisor, we can help coordinate the entire process so everything works together.
We specialize in helping dentists across Canada protect their practices through customized buy-sell strategies. Whether you’re starting a new practice, bringing in a partner, or reviewing your current agreement, we’ll guide you every step of the way.
Coming into an inheritance is a strange mix of feelings. There is often grief, because the money usually comes after losing someone you care about. There can also be relief, pressure, or even guilt. On top of all that, you may feel a quiet panic about doing the right thing with the money.
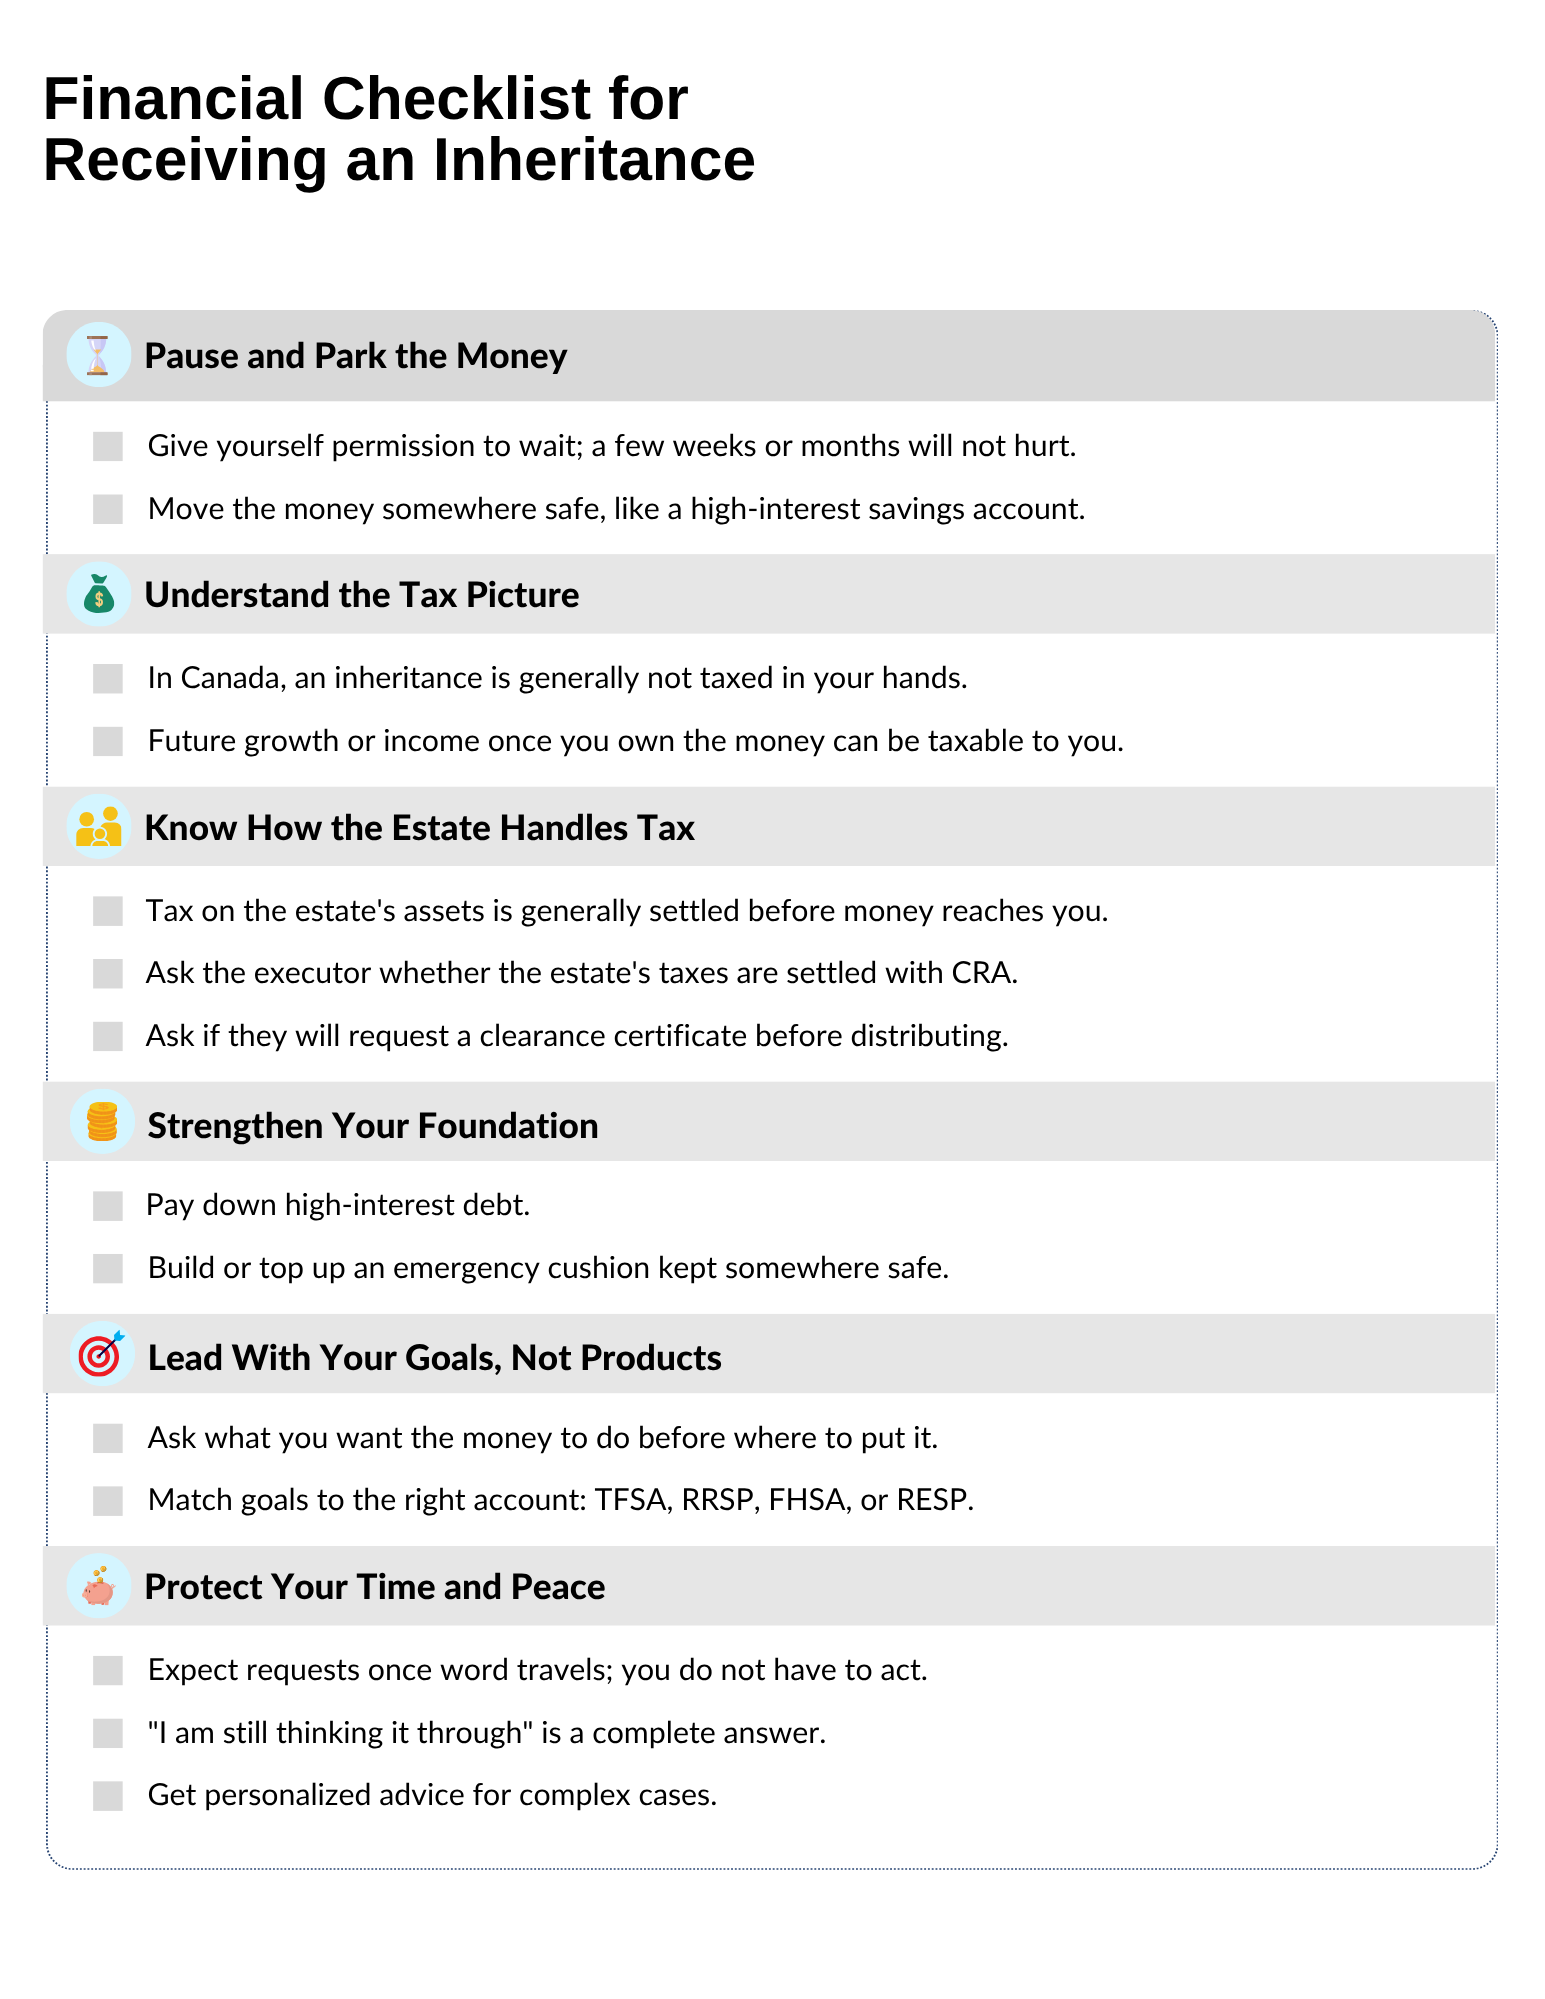
Here is the good news. You have more time than you think. The smartest first move is almost never a big move. Let us walk through what to do first, one calm step at a time.
There is no rush. Money that has been waiting in an estate is not going anywhere, and a few weeks or months of thinking time will not hurt you. In fact, that pause can save you from choices you might regret.
When a large sum lands in your account, it can feel like you should do something with it right away. Resist that pull. Big decisions made in the early days of grief or excitement are often the ones people wish they could undo.
For now, put the money somewhere safe and boring. A high-interest savings account is a good home. Your money stays easy to reach, it is protected, and it earns a bit while you think. There is no need to invest it, lend it, or spend it until you have had time to plan with a clear head.
This part surprises a lot of people, in a good way. In Canada, an inheritance is generally not taxed in the hands of the person who receives it. You usually do not report the money you inherit as income, and you do not pay tax just for receiving it.
Why is that? Because the tax is generally settled by the estate before the money reaches you. When someone passes away, their final tax return is prepared, and any tax owing on their assets is handled at that stage. The money is usually distributed to family and other heirs after that step. So by the time it gets to you, the tax piece has generally already been dealt with.
This does not mean money you inherit is tax-free forever. Once you own it, any future growth, interest, or income it earns can be taxable to you, just like your other money. But the act of inheriting it, on its own, generally does not create a tax bill for you.
For most people receiving an inheritance, the reassuring part is that this tax work happens at the estate level, not yours. You usually do not pay tax just for receiving an inheritance. If you would like to understand what happens behind the scenes, here is what happens to different assets before they reach you. The rules depend on the type of asset.
For non-registered assets, such as an investment account or a property that is not a primary home, assets are generally deemed disposed at fair market value on death, and accrued gains are reported on the final return unless a spousal rollover applies. The rollover works like this: these assets can roll to a spouse or common-law partner, or a qualifying spousal trust, on a tax-deferred basis. Otherwise, the accrued gain is reported on the final return.
For an RRSP or RRIF, the full value is generally treated as received and added to income on the final return, except where a spouse or common-law partner is a successor annuitant or receives an eligible rollover, or where a financially dependent child or grandchild qualifies for a rollover.
For a TFSA, growth inside a TFSA is tax-free to the date of death. A spouse or common-law partner named as successor holder can continue it tax-free, where that option is available. A named beneficiary follows set steps, and later growth can be taxable.
One simple thing is worth doing as a beneficiary: it is fair to ask the executor whether the estate’s taxes are settled, and whether they have requested a clearance certificate, before the estate is fully wound up. A clearance certificate is CRA’s confirmation that the estate’s taxes are paid, and it is something the executor may want to request before distributing the estate.
Once you have paused and you understand the tax basics, you can start to think about using the money well. Two steps tend to give the best return for the least worry.
The first is paying down high-interest debt. Credit card balances and other costly loans can quietly drain your budget every month. Clearing them is like giving yourself a guaranteed return, because you stop paying that interest for good. Few investments can promise that.
The second is building or topping up an emergency cushion. This is simply cash set aside for surprises, kept somewhere safe and easy to reach, like that high-interest savings account. A solid cushion means the next car repair or job hiccup does not throw your life off track. Together, clearing costly debt and holding a cash buffer give you a calm, steady base before you do anything fancier.
It is tempting to jump straight to “where should I put this money?” A better question is “what do I want this money to do for me?” Goals come first. Products come second.
Maybe you want to retire a little sooner, buy a first home, save for a child’s schooling, or just feel more secure. Once your goals are clear, registered accounts can help you reach them, and each one has a job:
A TFSA lets your savings grow tax-free, and you can take money out for any purpose.
An RRSP is built for retirement and can lower your taxable income in the year you contribute.
An FHSA is designed to help you save toward a first home.
An RESP helps you save for a child’s education after high school, with government grants that add to what you put in.
Each account has its own contribution room and rules, and these change over time. You can check your available room and the current limits through CRA My Account or at canada.ca. Matching the right account to the right goal is what turns a windfall into lasting progress.
If your situation involves cross-border elements, such as inheriting foreign property, or executors or beneficiaries in different countries, the tax picture can be more complex and may involve foreign reporting or foreign estate taxes. That is one of the times when personalized advice is well worth it.
A sudden sum of money can change how people treat you, and how you feel. Word travels. You may get requests for loans, gifts, or “can’t-miss” opportunities. You may also feel pressure inside your own family about what the money should be used for.
None of that means you must act. It is your inheritance, and you are allowed to take your time. A simple, kind answer works well: “I am still thinking it through.” That one sentence buys you space and protects you from rushed choices.
Coming into money you did not plan for is a lot to hold, especially when it follows a loss. So go gently. Park it somewhere safe, remember that your inheritance is generally not taxed to you when you receive it, and let your goals lead the way. The single best first step is often the simplest one: give yourself permission to pause. What would feeling truly settled with this money look like for you?
This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such.
Sources:
A new baby brings a lot of joy, and a lot of new to-do lists. Most of them are about feeding schedules and car seats. But a few items on the list are about money, and they matter more than you might think.
You do not need to do everything at once. A newborn keeps you busy enough. The steps below can be spread out over the first few months. Think of this as a simple checklist you can come back to as you find the time and energy.
A beneficiary is the person who receives the money from your life insurance or certain registered accounts after you pass away. Many people set these up years ago and never look at them again.
Now is a good time to check. You may want to add your partner, update an older choice, or think through how money should be handled for your child. If you want money to go to a minor child, it may need to be managed through a trustee or other legal arrangement until the child is of age, depending on the asset and the province.
The key point is simple. Look at every policy and account that names a beneficiary, and make sure the names and instructions still match the life you have today.
When it was just you, or just you and your partner, a gap in income may have been easier to manage. With a baby who depends on you, the stakes are higher. Life insurance can help protect your family financially if something happens to you, so they can keep up with housing costs, bills, and daily expenses.
For many young families, term life insurance is a common starting point. It covers you for a set number of years, often when your children are young and your financial obligations are highest. The premiums are usually lower than permanent coverage, which can make it easier to fit into a new-parent budget.
Your need for coverage often increases when you have a child. It is worth checking whether your current coverage, including any through work, would be enough to support your family for more than just the short term.
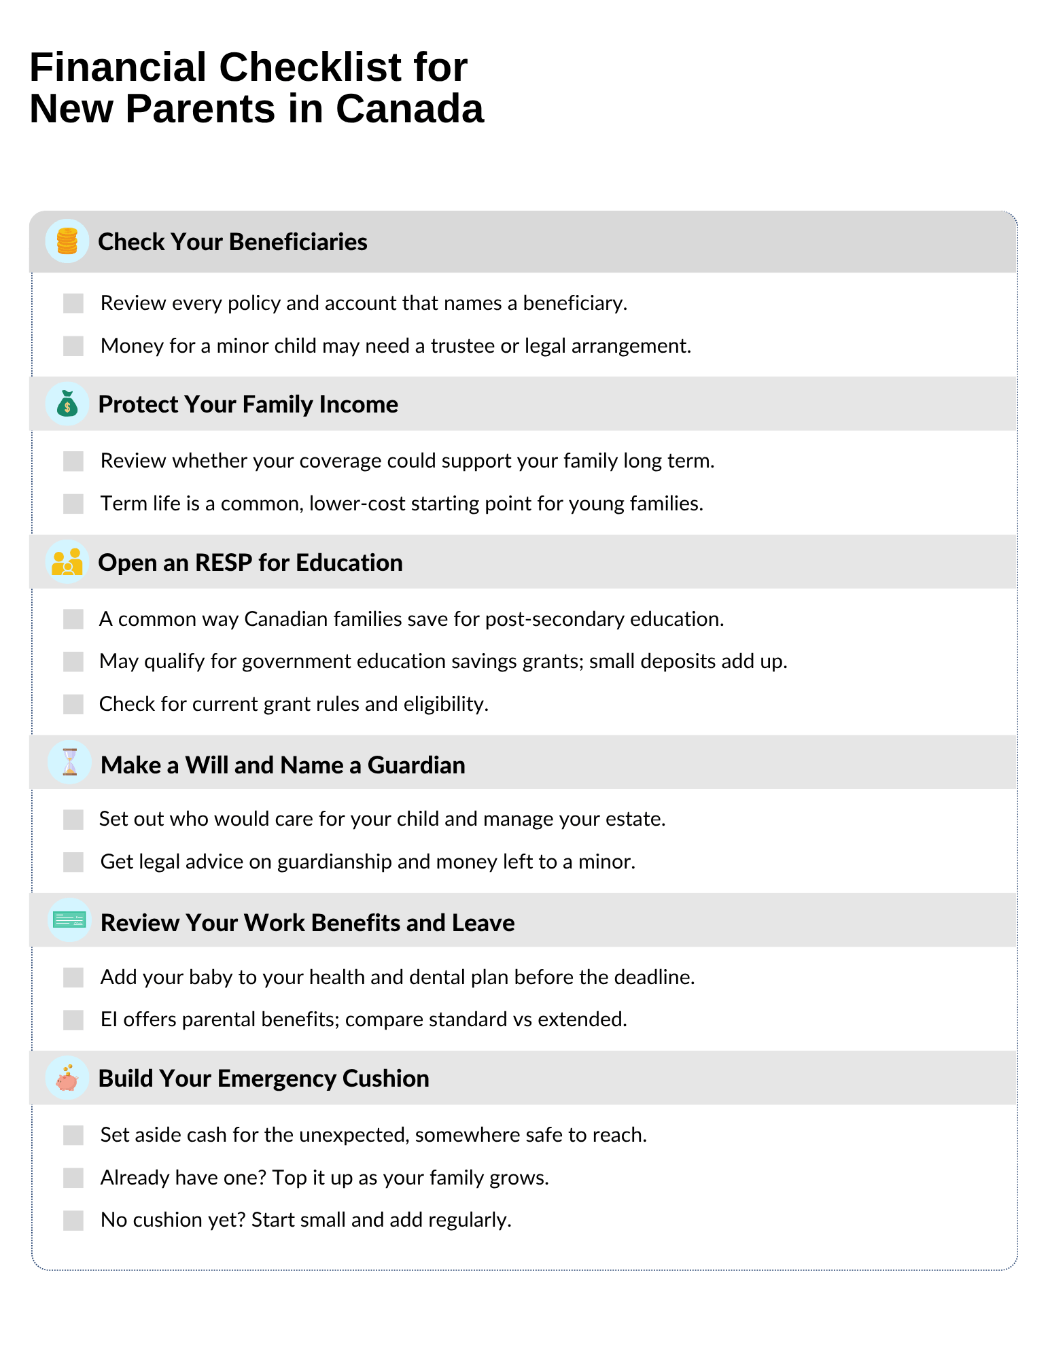
A Registered Education Savings Plan, or RESP, is a common way Canadian families save for a child’s post-secondary education. One reason many parents use it is the government support that can come with it through education savings grants.
You do not need a large amount to begin. Even small, regular deposits can add up over time. Check canada.ca for the current grant rules, contribution details, and eligibility requirements.
This is the step many new parents put off, and it is one of the most important. A will helps set out who would care for your child and how your estate should be handled if you and your partner die.
For parents, the most important part is often naming the person you want to care for your child. In BC, a will can express your wishes about guardianship, but it is also important to work with proper legal advice so your will deals clearly with both the care of your child and the management of any money left to a minor.
If you already have a will, a new baby is a good reason to review it. Add your child, confirm your choices, and make sure your estate plan still reflects your wishes.
Your job may offer more help than you realize. Many group benefit plans allow you to add a new dependent, but the deadline depends on the plan. Check with your human resources team or plan administrator as soon as possible after the birth so you do not miss the deadline for health and dental coverage.
Employment Insurance, or EI, also offers maternity and parental benefits for eligible parents. Parents can choose standard or extended parental benefits, and the timing and number of weeks differ between the two options, so it is important to review the current rules before applying.
A baby comes with surprises, and some of them cost money. An emergency cushion is simply cash set aside for the unexpected, kept somewhere safe and easy to reach.
If you already have one, this is a good time to top it up. A larger family often means larger surprise costs. If you do not have one yet, start small. Even a modest amount set aside regularly can help keep a rough week from becoming a money crisis.
That is a full list, and you do not have to tackle it all at once. Pick one item this week. Maybe it is checking a beneficiary, or asking work about adding your baby to your benefits. Small steps, taken one at a time, can help build a stronger financial foundation for your growing family.
This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such.
Sources:

Most people buy life insurance for one reason: to make sure their family is protected if something happens to them. But there is a type of life insurance that does something more – it builds value over time while you are still alive. That type is called participating whole life insurance, and it works very differently from the term policies most Canadians are familiar with.
Here is what it means, how it works, and whether it might be a fit for you.
Term life insurance covers you for a set period – 10, 20, or 30 years. Participating whole life insurance is permanent. It covers you for your entire life, as long as premiums are paid, and the death benefit is guaranteed.
That permanence is the first major difference. But the bigger difference is what happens to your premiums while you are alive.
With a term policy, your premiums go entirely toward the cost of insurance. With participating whole life, the insurer pools premiums into a participating account that is professionally managed. Dividends may be paid when the account’s experience is favourable, based on factors such as investment returns, expenses, and mortality experience.
The word “dividend” here is different from stock dividends. In the context of a participating whole life policy, a dividend is a share of the insurance company’s surplus – essentially, the company returning a portion of the money when investment performance, claims experience, and expenses go better than expected.
These dividends are not guaranteed. They are declared each year by the insurance company based on how the participating account performed. That said, many Canadian participating insurers have long histories of paying dividends, though past performance does not guarantee future results.
When you receive a dividend, you have a few options for how to use it:
Take it as cash. The dividend is paid to you directly.
Apply it to your premium. It reduces how much you pay out of pocket.
Buy additional paid-up insurance. This is the most common choice. The dividend purchases more coverage, which in turn earns its own dividends. Over time, this compounds.
Leave it on deposit. The dividend sits with the insurer and earns interest.
Most policyholders who hold participating whole life for the long term choose to purchase additional paid-up insurance, because it accelerates both the death benefit and the cash value of the policy.
One of the most distinctive features of a participating whole life policy is that it builds cash value. The policy builds guaranteed cash value as part of its structure, and dividends can add a non-guaranteed layer of growth if they are used to buy paid-up additions.
The policy accumulates cash value that you may be able to access, subject to policy terms, in a few ways:
Policy loans. You can borrow against the cash value without going through a lender or credit check. Policy loans do not have fixed repayment schedules, but any unpaid balance can reduce the death benefit.
Surrendering the policy. If you decide you no longer need the coverage, you can cancel the policy and receive the accumulated surrender value. The tax treatment on surrender can be technical and depends on the policy’s adjusted cost basis — the disclaimer at the end of this article applies here.
The cash value grows on a guaranteed basis, separate from the dividends. The dividends, if used to purchase paid-up additions, add a non-guaranteed layer of growth on top.
Participating whole life is not the right fit for every situation. Because premiums are higher than term insurance, it is most commonly used by people who have a long-term need for life insurance and who can sustain the premium over time.
Some of the most common situations where it makes sense:
Families building long-term wealth. For parents who want to ensure a guaranteed death benefit no matter when they pass, plus build a tax-advantaged asset over decades, participating whole life offers both.
Business owners and incorporated professionals. A participating whole life policy held inside a corporation may offer a tax-efficient approach to building cash value inside a permanent policy, depending on the structure and the corporation’s specific situation. It can be used by incorporated professionals – such as dentists and physicians – to redirect excess corporate cash into a long-term, protected asset.
Estate planning. For those who want to leave a specific, guaranteed sum to their heirs or a charitable organization, a participating whole life policy creates a known outcome – the death benefit- regardless of when death occurs.
High net worth individuals. When other registered accounts (TFSA, RRSP) are maximized, participating whole life can offer a tax-efficient way to build cash value inside a permanent policy, outside of registered limits.
Term and participating whole life insurance are not competitors- they serve different purposes, and many Canadians use both at different stages of life.
Term insurance is a straightforward, affordable way to protect your family during the years it matters most – while a mortgage is being paid down, while children are young, or while income replacement is the primary concern. It does exactly what it is designed to do.
Participating whole life steps in when the need for coverage is permanent, when building long-term cash value matters, or when the policy is part of a broader estate or corporate strategy. The two products often complement each other well, and choosing one does not mean ruling out the other.
Participating whole life insurance combines permanent death benefit protection with a growing cash value and the potential for dividends. It is a longer-term commitment with higher premiums, and it is designed for situations where permanence, cash value, and legacy planning are part of the picture.
If you are considering permanent life insurance, take time to review how dividend performance has held up at the insurer you are looking at, understand the various dividend options, and think through whether the long-term commitment fits your situation.
This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such. Policy design, dividend scale performance, cash value growth, and tax treatment vary by insurer and by the specific policy contract. Always review the policy illustration and contract terms carefully.
Sources:
Blended families – where two people get married but have children from previous relationships – are becoming more common. It can be challenging enough to take care of the everyday logistics; from where to live to making sure everyone gets along. So trying to make sure you properly take of estate planning often doesn’t get taken care of.
In most families – blended or not – spouses leave everything to each other. Then, when the surviving spouse dies, the remainder is divided amongst all of the children. The problem with this setup is that there is no guarantee that the surviving spouse will not remarry and inadvertently disinherit the deceased’s children.
To make sure that everyone is treated fairly, it’s essential to consider how to handle each of the following estate planning issues for blended families:
It’s essential to have a full discussion with your spouse and children to avoid misunderstandings and reduce uncertainty. But you don’t have to do it alone! We can provide you with tailored solutions to ensure your wishes are carried out.
This can be challenging, depending on whether the blended family moves into a new home or into a house one spouse already owns. An option to consider is that the spouse who is moving into the home already owned by the other spouse can then purchase an interest in the family home. If this occurs, each spouse can own the home as tenants-in-common, enabling them to manage their interest in the house separately.
When it comes time for each spouse to draw up a will, provisions can be made for the surviving spouse to remain in the home until the time of their choosing (or death) before passing on the interest to their respective children.
The best way to take advantage of the tax-free rollover from an RRSP is for each spouse to name each other the beneficiary. While it may be tempting to leave your RRSP to your estate or one or more of your children, this can have ramifications. If you leave it to your estate, it will have to go through probate and also be taxed. If you leave it an adult child, the RRSP won’t have to go through probate, but the entire RRSP will be considered taxable to the deceased in the year of death.
You can set up your estate planning so that your spouse can benefit from income-producing assets during their lifetime, without necessarily impacting the capital in those assets. Your children can then benefit from them after your spouse dies.
Each spouse can set up a spousal testamentary trust to contain their income-producing investments and assets. The surviving spouse will then receive all the income from the trust and the option to access the capital for specific needs (if specified in the trust). After the surviving spouse dies, the assets will pass to whoever was identified as the trust’s inheritors. You can make the inheritors your children. This ensures that both your spouse and your children are taken care of.
Trusts are a vital part of effective estate planning for blended families. This means that it’s critical to pick the right trustee – as they will control and manage the assets of the deceased’s estate as outlined in the deceased’s will. You may even want to consider multiple trustees or the services of a trust company. A strong but neutral trustee will help ensure that your wishes are followed without causing fighting amongst family members.
There are several advantages to using life insurance policies as part of your estate planning for blended families:
No matter what choices you make about estate planning for your blended family, you must communicate openly and honestly with everyone in the family. This will help ensure that everyone is aware of the state of affairs and reduces misunderstandings and uncertainty about what the future may hold for everyone in the family.
Using professional advice while you are estate planning for blended families can help you create a solution that satisfies both spouses and their respective children’s objectives. Reach out to me if you have any questions or concerns about your estate planning – I’m here to help!
Building a Bright and Sustainable Future Together
As a small business owner, you recognize the significance of looking after your team and fostering a nurturing work environment. One method to demonstrate this is by providing a robust group benefits plan. This not only reflects your dedication to your team’s well-being but also is instrumental in drawing and retaining the best talent. Dive into the realm of group benefits and discover how to select and tailor the ideal plan for your small enterprise.
Understanding the Basics of Group Benefits
Group benefits plans are crafted to offer a variety of health, financial, and wellness advantages to your team members. These packages can encompass health and dental insurance, life and disability insurance, retirement savings alternatives, and more. The main benefit of a group benefits plan is its ability to distribute the risk among your team, making coverage more cost-effective and reachable for all.
Step 1: Assess Your Business Needs
Before diving into a group benefits plan, it’s vital to evaluate the requirements of your business and your team. Ponder over these questions:
Step 2: Collaborate with a Benefits Specialist
Teaming up with a benefits specialist is akin to having a navigator on your quest to devise the perfect plan. They will assist you in traversing the intricate landscape of insurance choices, rules, and compliance mandates. They’ll engage closely with you to grasp the distinct needs of your business and craft a plan that matches your budget and principles.
Step 3: Customize Your Plan
Adaptability is paramount when shaping a benefits plan that appeals to your team. Here are some avenues for personalization:
Step 4: Educate Your Employees
The efficacy of a group benefits plan hinges on transparent communication and enlightenment. Ensure your team comprehends the worth of the benefits provided and the methods to utilize them optimally. Arrange seminars, online sessions, or informational meetups to aid them in making knowledgeable choices about their coverage.
Step 5: Regularly Review and Adjust
The dynamics of your business and the needs of your team will transform over time. Hence, it’s crucial to revisit your group benefits plan annually and make requisite modifications. This guarantees that your plan stays in sync with your objectives and consistently delivers value to your team.
Building a Sustainable Future Together
As you embark on the path of picking and personalizing a group benefits plan for your small enterprise, bear in mind that your collaboration with your team is central to the process. By placing their welfare at the forefront and presenting a comprehensive benefits package, you’re not merely paving a brighter path for your team but also cultivating a sustainable work setting that promotes allegiance, efficiency, and expansion.
If you cannot work because you are seriously injured or ill, disability insurance will provide you with a monthly, tax-free income to help replace your lost wages. An injury does not have to be as blatant as a broken leg or arm – suffering from chronic pain or dealing with mental health issues can also qualify you for a disability insurance payout.
Why do I need disability insurance?
Unfortunately, people become disabled – whether temporarily or permanently – quite often. In 2017, over 20 percent of Canadians had one or more disabilities.
If you’re disabled, you may lose one of your most valuable assets – your ability to work and bring in a paycheck. Disability insurance can help replace that paycheck for as long as you need it to. Being able to rely on a disability insurance payout means you won’t have to dip into your savings if anything happens to you.
Disability insurance is especially important if you are self-employed, particularly if you are the family’s sole income earner.
What if I already have disability insurance through work?
If you have disability insurance through work, that’s great – but it may not replace 100 percent of your paycheck, especially if you’re off work for a long time. If you purchase private disability insurance, you can:
Having private disability insurance will give you peace of mind that you either have additional coverage if you are employed and at least some disability coverage if you lose your job.
How does disability insurance work?
We’d be happy to answer any questions you have about disability insurance. There are five main steps to disability insurance:
We’re Here To Help
If you’d like to know more about disability insurance – from how much it would cost you to what you can file a claim for – we’re here to help! Give us a call today.
As a financial advisor, my primary goal is to help you achieve financial clarity. I do this by accessing a network of dedicated professionals, each bringing their unique expertise to the table. Together, we provide personalized advice and services that help you make informed decisions and secure your future.
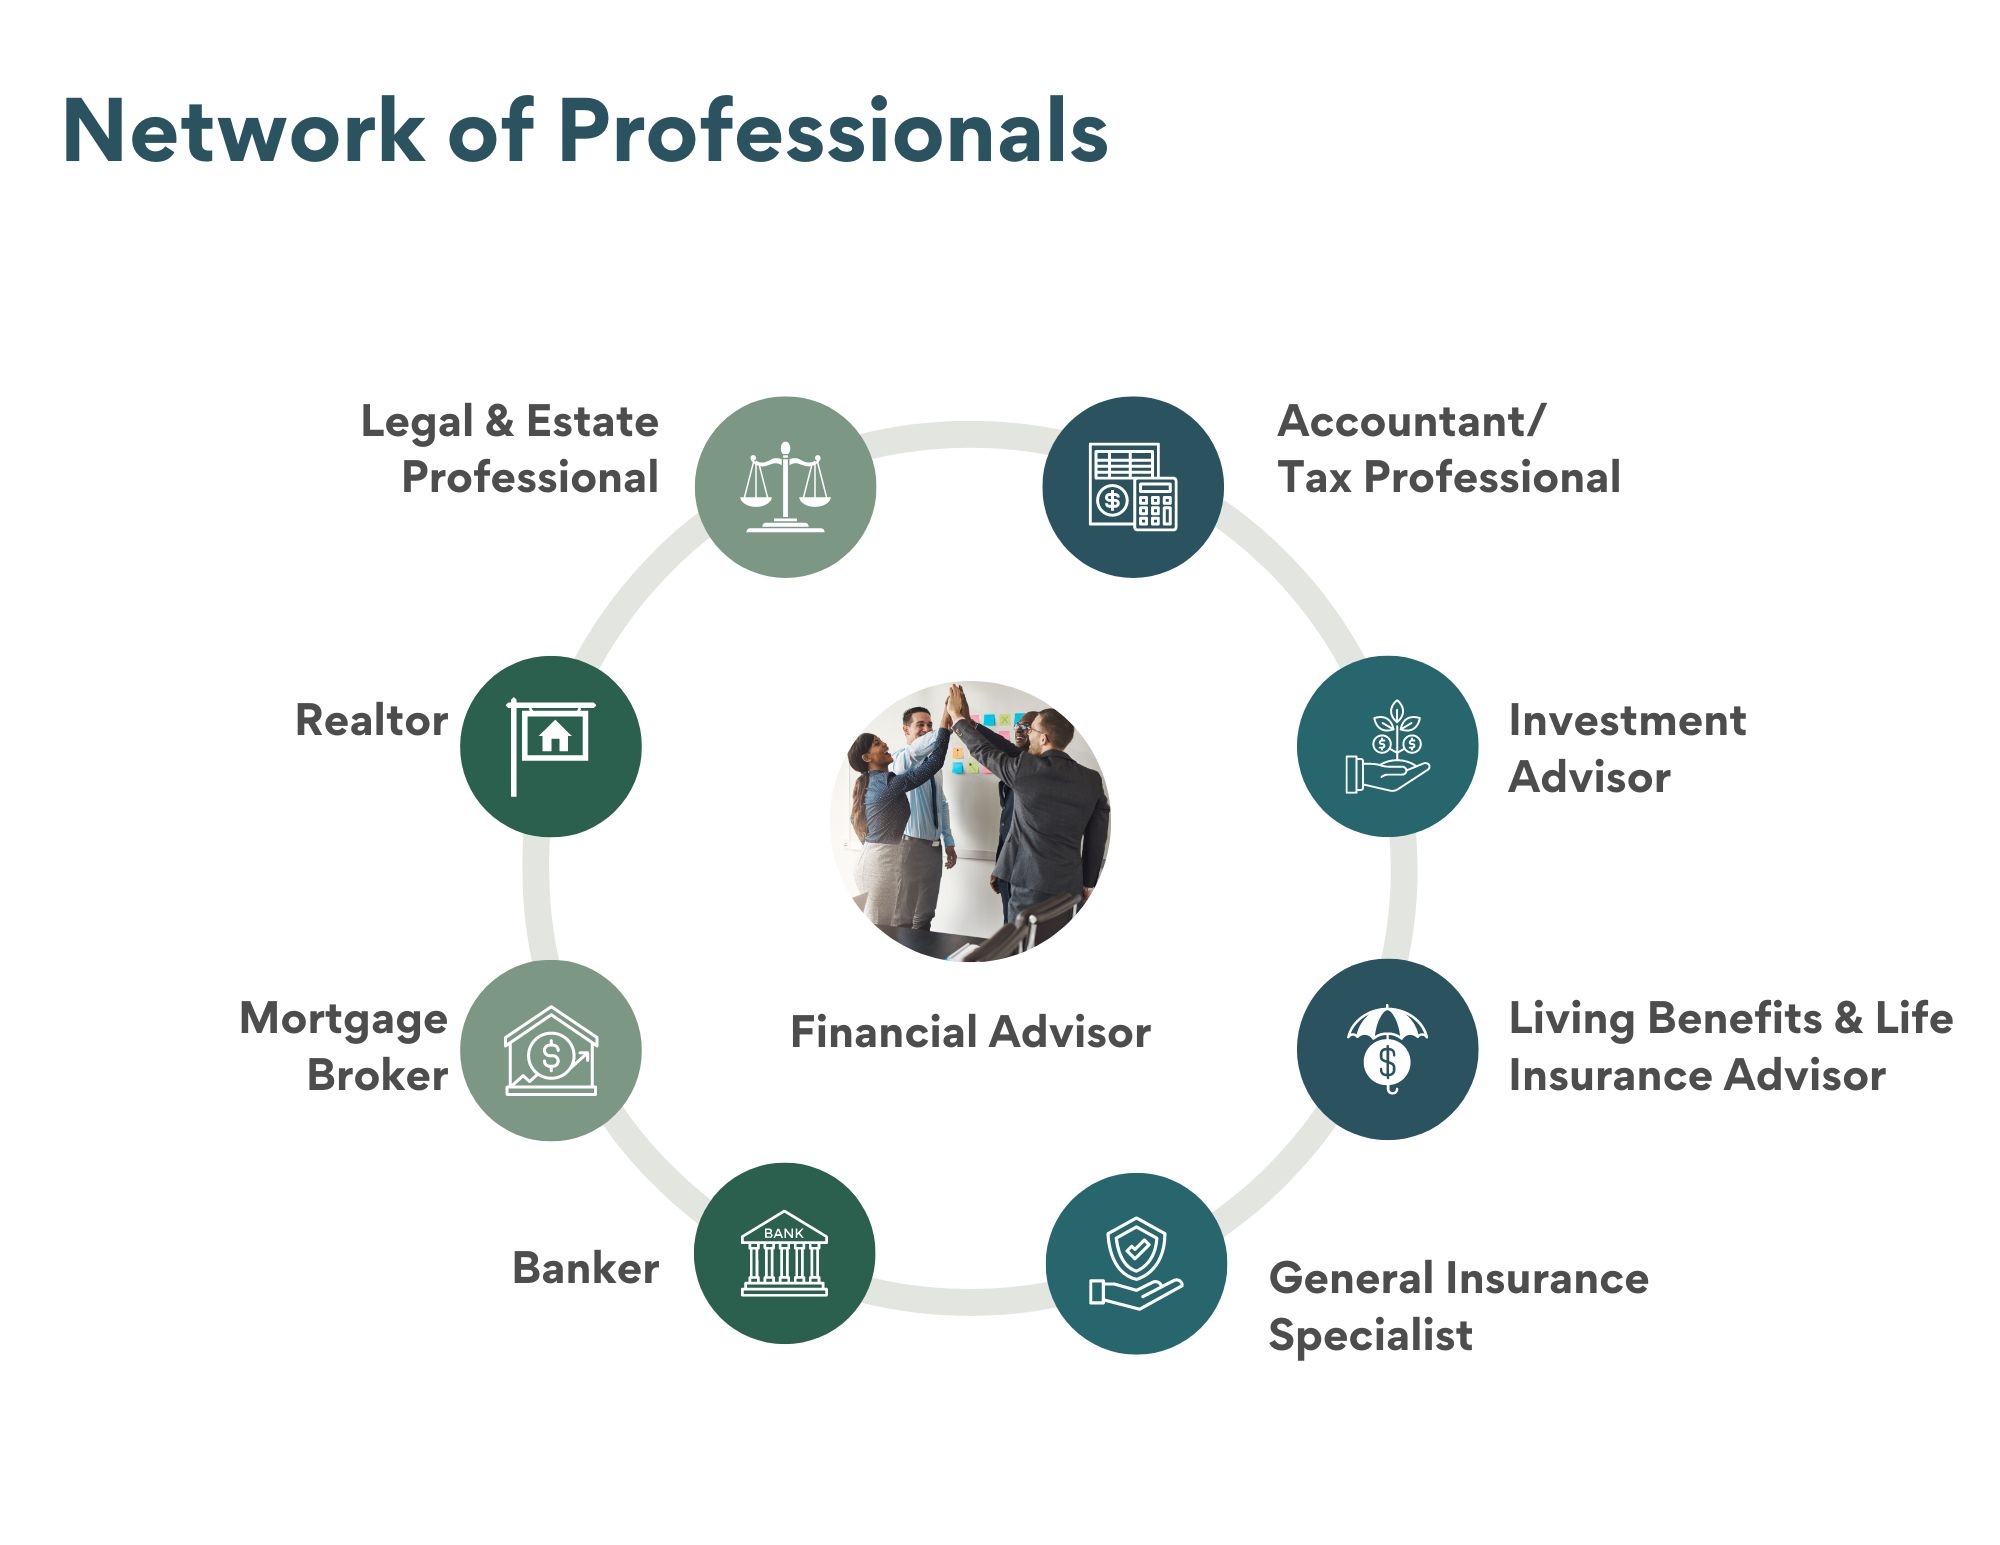
Think of me as your financial coordinator. I help you figure out your goals, create plans to achieve them, and keep everything on track. Whether it’s planning for retirement, managing investments, or saving for a major purchase, I have access to a network of professionals who ensure every aspect of your financial life works together smoothly.
Having an accountant or tax professional in your financial network is essential for keeping your financial records in order. They handle tasks like bookkeeping, preparing financial statements, and assisting with tax planning. Their role is particularly important during tax season. They help you file your taxes accurately and on time, taking the stress out of the process. By optimizing your tax strategies and ensuring everything is reported correctly, they help you save money. Their skills are invaluable for both your immediate needs and long-term financial planning.
Investment advisors focus on building and managing investment portfolios tailored to your short-term, medium-term, and long-term goals. They thoroughly research the market, evaluate investment opportunities, and offer valuable insights to help you create a well-rounded portfolio. Whether you’re saving up for a major purchase, planning for retirement, or aiming for other financial milestones, they assist in choosing the right investment vehicles, such as RRSPs, TFSAs, RRIFs, and non-registered accounts, to support your financial stability and future needs.
Life insurance and living benefits advisors are here to help you protect your greatest asset: yourself. Their job is to make sure you and your family are financially secure if unexpected events occur. These advisors walk you through different insurance options, including disability insurance, critical illness insurance, and life insurance, to find the coverage that fits your needs best. By understanding your unique situation and recommending the right policies, they provide you with peace of mind, knowing that you have a safety net in place for life’s uncertainties.
General insurance specialists cover a wide range of insurance needs, including auto, property, travel, and liability insurance. They assess your risks and recommend policies that provide the protection you need. Their advice helps you understand your options, compare quotes, and select the best policies to safeguard your assets, ensuring you are well-protected in various aspects of your life.
Bankers are there to help you navigate a wide range of financial services, especially when it comes to getting loans and credit products. They offer advice on securing personal loans, understanding credit options, and managing debt effectively. Whether you’re looking to finance a major purchase, consolidate debt, or build your credit, bankers provide the support and guidance you need to make informed financial decisions.
Mortgage brokers assist you in securing financing for property purchases by accessing multiple lenders on your behalf. They assess your financial situation, compare mortgage products from various sources, and recommend the best options for you. With their ability to shop around and understand different interest rates, loan terms, and application processes, they ensure you get the best possible mortgage deal, making homeownership more accessible and affordable.
Realtors are your go-to professionals for buying or selling property. They provide market insights, negotiate deals, and manage the legal aspects of real estate transactions. With their knowledge of local market trends and property values, realtors help you make informed decisions whether you’re purchasing a home, investing in real estate, or selling property.
Legal and estate professionals play a vital role in your financial planning by handling the legal side of things, such as estate planning, wills, trusts, and probate. They make sure your assets are distributed according to your wishes and that all the necessary legal documents are properly set up. Their guidance helps you reduce estate taxes and smoothly navigate the legal processes, ensuring your wealth is transferred to future generations just as you intended.
Having a network of financial professionals is essential for achieving financial well-being. Each member brings their own expertise to address different aspects of your finances, from investments and insurance to legal and real estate matters. As your financial advisor, I act as the coordinator, ensuring that all these professionals work together seamlessly. By leveraging their combined knowledge and skills, you can gain financial clarity and know that every aspect of your financial life is taken care of.
Ready to take control of your financial future? Contact us today.


